Owner financing means the person selling the house lends you the money to buy it. Instead of going to a bank for a mortgage, you make monthly payments directly to the seller. You still own the home — the title can be in your name from day one — but the seller holds the financial note instead of a bank.
It’s a legitimate, legal way to buy a home in Tennessee. For buyers who don’t qualify for traditional loans, it’s often the only path to homeownership.
What Owner Financing Is — and How It’s Different from a Bank Loan
Owner financing is a home purchase agreement where the seller, not a bank, provides the financing. The seller and buyer agree on a price, down payment, interest rate, and term. The seller transfers the property, and the buyer makes monthly payments directly to them.
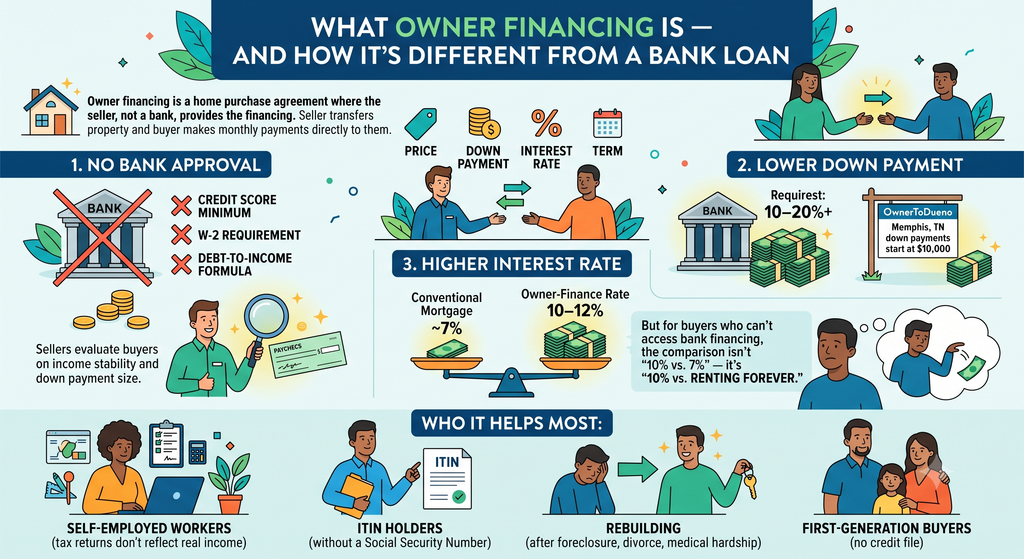
The main differences from a bank loan:
No bank approval. No credit score minimum, no W-2 requirement, no debt-to-income formula. Sellers evaluate buyers on income stability and down payment size.
Lower down payment. Banks require 10–20%+. On OwnerToDueno listings in Memphis, down payments start at $10,000.
Higher interest rate. Owner-finance rates in Memphis run 10–12% — higher than a conventional mortgage. But for buyers who can’t access bank financing at any rate, the comparison isn’t “10% vs. 7%” — it’s “10% vs. renting forever.”
Who it helps most: Self-employed workers whose tax returns don’t reflect real income. ITIN holders without a Social Security Number. Buyers rebuilding after foreclosure, divorce, or medical hardship. First-generation buyers with no credit file.
How the Process Works: Step by Step
Step 1 — Find a property. Browse ownertodueno.com. Every listing shows the asking price, down payment, estimated monthly payment, and property details. Current inventory runs from $159,000 in North Memphis (38128) to $289,000 in Cordova (38018).
Step 2 — Contact the team. A team member walks you through the exact terms: down payment, interest rate, 30-year term, and estimated monthly payment.
Step 3 — Submit your application. Not a credit check — a verification of income and available down payment. Bank statements or pay stubs work. Response in 24–48 hours.
Step 4 — Agree on terms in writing. Purchase price, down payment, fixed interest rate (10–12%), 30-year term, monthly payment amount, and the default process. Read this section carefully.
Step 5 — Close at a licensed title company. Every OwnerToDueno transaction closes through Bradsher, Albert & Stuart, PLLC — a licensed Tennessee attorney firm and title company in Memphis. They conduct the title search, hold your down payment in escrow, record the deed of trust with Shelby County, and give both parties every signed document.
Step 6 — Make monthly payments and build equity. After closing, you’re the homeowner — you maintain the property, pay taxes and insurance, and make improvements. After 30 years, the note is paid off and the property is fully yours.
Common Risks and Misunderstandings
“The seller can take my house back whenever they want.”
Not with a properly recorded deed of trust. The seller must go through Tennessee’s formal foreclosure process — months of legal procedure, required notices. The protection is the recording. If anyone asks you to sign without a title company, walk away.
“Owner financing is a scam.”
It can be — when done informally, without a recorded contract. The protection is always the same: close through a licensed title company, get a recorded contract, keep your paperwork.
“I’ll definitely own the title from day one.”
Depends on the contract. With a warranty deed: title transfers to you at closing, seller holds a lien. With a contract for deed (land contract): seller retains title until a specified amount is paid. Both are legal in Tennessee — know which one you’re signing.
“The rate is too high.”
10–12% is higher than a bank rate. But if you’re currently paying $1,500/month in rent and building zero equity, a $1,600/month owner-finance payment that builds ownership is a different financial picture entirely.
“Missing a payment won’t matter.”
It works exactly like a bank mortgage. After a grace period you go into default. Private lenders have more flexibility than banks — but only if you communicate early.
Frequently Asked Questions
Do I need a Social Security Number to use owner financing in Memphis?
No. An ITIN is sufficient to sign contracts and take title to property in Tennessee. Many OwnerToDueno buyers are ITIN holders who pay taxes, have stable income, and have been renting for years. Owner financing is the path that works for them.
What down payment do I need?
Down payments on OwnerToDueno listings start at $10,000. Properties in the $200,000–$289,000 range typically require $15,000–$20,000. The exact amount is on each property listing page.
Who holds the title during the financing period?
In most OwnerToDueno transactions, the title transfers to the buyer at closing via a warranty deed. The seller holds a lien — a deed of trust — not the title itself. Your name is on the property from day one.
What if I want to sell before the note is paid off?
Most owner-finance contracts include a due-on-sale clause. When you sell, the proceeds pay off the remaining balance to the seller. You keep whatever equity is above that — same as paying off a bank mortgage at sale.
Can sellers list owner-financed properties on OwnerToDueno?
Yes. OwnerToDueno connects sellers who want to carry financing with qualified buyers. Every transaction still closes through a licensed title company, protecting both sides.
Ready to Buy or List?
Browse current owner-financed homes at ownertodueno.com — Cordova, Bartlett, South Memphis, Midtown, and across the Memphis metro, down payments starting at $10,000.