Category: Memphis real estate

  • 4-Bed Home in Memphis, TN 38134 | $239,000, $20K Down | Dueño a Dueño

    4-Bed Home in Memphis, TN 38134 | $239,000, $20K Down | Dueño a Dueño

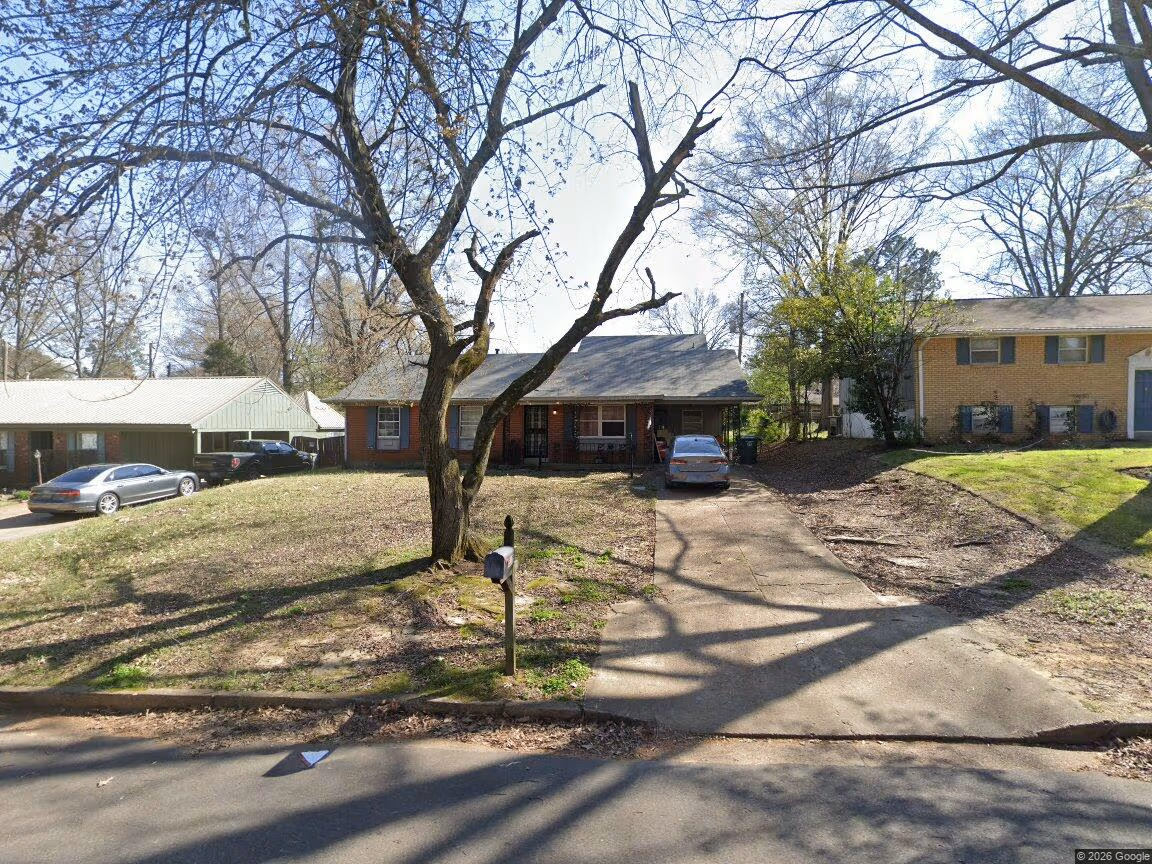
    Quick answer: Rolling Fields Dr. in Memphis, TN 38134 is a 4-bedroom, 2-bathroom single-family home with 1,587 square feet of living space, built in 1962. The price is $239,000, the listed monthly payment is $2,341, and the down payment is $20,000. The owner sells directly through Dueño a Dueño, so there is no bank in the middle.

    Most people shopping for a family home in Memphis run into the same wall: the bank says no, or says yes with a pile of conditions. This house is a different route. Let’s walk through what it offers, what the numbers mean, and what to check before you commit.

    5175 Rolling Fields Dr at a glance

    DetailInformation
    AddressRolling Fields Dr, Memphis, TN 38134
    Price$239,000
    Monthly payment$2,341
    Down payment$20,000
    Bedrooms4
    Bathrooms2 full
    Living area1,587 sq ft
    Year built1962
    Property typeSingle-family residence
    SellerOwner, through Dueño a Dueño

    The listing page shows this home as “coming soon” at the time of writing, so open the full listing for the latest availability.

    What the house offers

    Four bedrooms and two full bathrooms is a layout that works for a lot of households. A growing family gets a room for everyone. A couple working from home can turn one bedroom into an office and still have a spare. Two bathrooms also take real pressure off a busy morning, which anyone who has shared one with three other people will appreciate.

    At 1,587 square feet, the space is practical rather than huge. It was built in 1962, so expect the character of a mid-century Memphis home, along with the kind of upkeep that comes with a house that age. More on that below.

    The address sits in the 38134 ZIP code in Memphis, Tennessee. If you want to see the neighborhood for yourself, you can book a tour from the listing page.

    Making sense of the $2,341 monthly payment

    The numbers are simple to state. The home costs $239,000. You put $20,000 down, which leaves $219,000 to be paid over time through the owner financing agreement. The listed payment is $2,341 a month.

    Here is a rough way to test whether that fits your budget. A common guideline is to keep housing costs near 30% of your gross monthly income. Working backward, a $2,341 payment lines up with an income of about $7,800 a month, or roughly $93,600 a year. That is a rule of thumb, not a rule. Your debts, savings, and family size matter just as much, so use it as a starting point.

    Two questions to ask the owner before you decide:

    • Does the monthly payment include property taxes and homeowners insurance, or are those separate?
    • What are the loan term, the interest rate, and any balloon payment, if there is one?

    A good owner-financed deal puts all of this in writing before you sign anything.

    Why buy directly from the owner?

    With a traditional purchase, a bank decides whether you qualify, sets the timeline, and adds fees along the way. With owner financing, you deal with the person who owns the home. Terms can be more flexible, the conversation is more direct, and the process is often faster.

    Dueño a Dueño is a Memphis marketplace built around that idea. Buyers and owners connect without banks or middlemen, and the site works in both English and Spanish. If you want to understand the whole picture first, browse the Dueño a Dueño blog or look through all available properties.

    What to do before you make an offer

    Buying a 1962 home is perfectly reasonable, as long as you go in with open eyes. A short checklist:

    1. Get an independent inspection. Pay attention to the roof, plumbing, electrical panel, HVAC, and foundation. Older homes can hide expensive surprises.
    2. Walk the property in daylight. Check the yard, the drainage, and the street at different times of day.
    3. Read the agreement carefully. Understand the payment schedule, late fees, and what happens if you want to refinance later.
    4. Consider a title check and an attorney review. It costs little compared with the size of the purchase.
    5. Budget for repairs. Setting aside money for the first year of ownership is smart on any home from this era.

    Compare it with other Memphis homes nearby

    It helps to see more than one option. These listings are close to Rolling Fields Dr:

    • 4697 Grecco Drive: about 1.5 miles away, 3 bedrooms, 1.5 bathrooms, 1,800 sq ft, listed at $184,000.
    • 5753 Antwerp Avenue East: about 1.7 miles away, 3 bedrooms, 2 bathrooms, 1,325 sq ft, listed at $249,000.

    Rolling Fields Dr stands out for the extra bedroom. If four bedrooms matter to you, that is the main difference.

    Who this home may suit

    • Families who need four bedrooms without a much higher price tag
    • Buyers who have steady income but a tough time with traditional bank approval
    • Spanish-speaking and bilingual households who want to handle the process in their own language
    • People who like the idea of talking straight to the owner

    Frequently asked questions

    How much is the house at 5175 Rolling Fields Dr in Memphis?

    The listed price is $239,000, with a $20,000 down payment and a listed monthly payment of $2,341.

    How many bedrooms and bathrooms does it have?

    It has 4 bedrooms and 2 full bathrooms across 1,587 square feet of living space.

    When was the home built?

    It was built in 1962 and is a single-family residence in the 38134 ZIP code of Memphis, TN.

    Do I need a bank loan to buy it?

    No. The home is offered through owner financing, so you work directly with the owner instead of a bank.

    How much do I need to put down?

    The listed down payment is $20,000.

    Can I tour the house before I apply?

    Yes. You can schedule a tour from the listing page, or call (901) 660-4100 to ask questions first.

    Is the listing available in Spanish?

    Yes. Dueño a Dueño works in English and Spanish, and this Spanish listing page has the full property details.

    Take the next step

    If a four-bedroom Memphis home with a $20,000 down payment sounds like a fit, the easiest next step is to see the property yourself. Open the listing for 5175 Rolling Fields Dr, schedule a tour, or start your application. Own a home and thinking about selling it directly? You can also list your property on Dueño a Dueño.
  • How Much Down Payment Do You Need for Owner Financing in Memphis?

    Most owner-financed homes in Memphis ask for a down payment of about 5% to 20% of the purchase price, and 10% is a common starting point. On a $150,000 house, that’s roughly $7,500 to $30,000. Some listings advertise as little as $10,000 or $20,000 down. Because the seller sets the terms, the number is negotiable.

    If you’ve been told “you need 20% down” and walked away from buying a home, you’re not alone. A lot of Memphis families hear that number, do the math, and quietly give up. The good news is that owner financing works differently. There’s no bank underwriting department deciding for you. You and the seller agree on a number that works for both sides. How Much Down Payment Do You Need for Owner Financing in Memphis?

    This guide explains how much down payment you should expect with owner financing in Memphis, TN, what changes that number, and how to figure out the right amount for your situation.

    Key Takeaways

    • Typical down payments on owner-financed homes in Memphis range from 5% to 20%, with 10% a common benchmark.
    • Owner financing with $10,000 down in Memphis is possible on lower-priced homes, and some sellers accept $20,000 on mid-priced homes.
    • The seller decides the terms, so the down payment, interest rate, and payment schedule can all be negotiated.
    • A bigger down payment usually means a smaller monthly payment and a stronger offer, but it isn’t always required.
    • Budget for closing costs, insurance, and repairs on top of the down payment.

    What Is a Down Payment in Owner Financing?

    A down payment is the cash you pay up front toward the price of the home. The rest of the price is what you owe the seller, and you pay it back in monthly installments with interest.

    In a bank mortgage, a lender approves you and funds the loan. In owner financing (also called seller financing or owner-to-owner financing), the seller acts as the lender. You make payments directly to them, or to a servicing company they use. That’s why this route is popular for no-bank home buying in Memphis: the seller decides whether your down payment, income, and payment history make sense, instead of a bank following a rigid checklist.

    What Is the Typical Down Payment for Owner-Financed Homes in Memphis?

    There’s no official standard, because every seller sets their own terms. In practice, you’ll usually see:

    • 5% to 10% on lower-priced homes or when the buyer has high, steady income
    • 10% to 15% as a common middle ground
    • 15% to 20% or more on higher-priced homes, or when the seller wants extra security

    Listings on OwnerToDueno show how this plays out. Some Memphis homes are advertised with only $10,000 down, and others with $20,000 down. Those figures are tied to the price, the property, and the seller’s goals, so always check the specific listing.

    What Does a Down Payment Look Like at Different Prices?

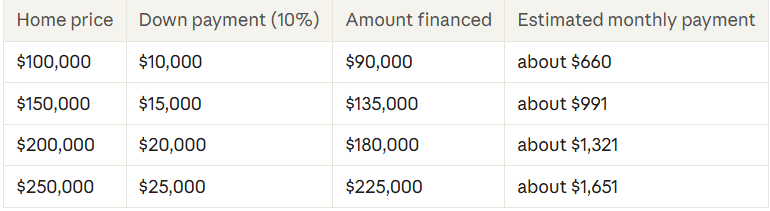
    Here’s a simple example of what 10% down looks like on common Memphis price points, with an estimated monthly payment. These numbers use an 8% interest rate and a 30-year term, and they cover principal and interest only. Taxes and insurance are extra, and your actual rate and terms will depend on the seller.

    If you’re shopping for homes under $150,000 with owner financing in Memphis, you can see how a $10,000 or $15,000 down payment can put you in the same range as a typical monthly rent. You can run your own numbers with the cash flow calculator on the seller page.

    Is It Worth Putting More Down?

    Sometimes yes, sometimes no. Here’s how the down payment changes the monthly payment on a $150,000 home, using the same 8%, 30-year assumptions:

    Going from 5% down to 20% down saves roughly $165 a month in this example. That’s real money over time. But it also means you need $22,500 more in cash on day one. If emptying your savings leaves you with no cushion for a broken water heater, a smaller down payment and a slightly higher monthly payment can be the smarter call.

    A good rule of thumb: put down as much as you comfortably can while keeping an emergency fund of at least a couple of months of expenses.

    What Decides How Much Down Payment You Need?

    Because the seller sets the rules, several things influence the number:

    1. The price of the home. A $70,000 house and a $350,000 house don’t carry the same risk, so the expectations differ.
    2. The seller’s situation. A seller who owns the home free and clear has more flexibility than one who still has a mortgage and needs cash.
    3. Your income and payment history. Some sellers weigh credit lightly and care more about steady income. Many still ask about both. A stronger profile can earn a smaller down payment.
    4. The condition of the property. A home that needs repairs may come with a lower price and a different down payment than a move-in-ready one.
    5. The interest rate and term. A seller may accept less down if the rate is higher or the term is shorter. It’s a trade-off, so ask to see a couple of versions.
    6. How motivated both sides are. Sellers who want steady monthly income and buyers who want a path to ownership usually find a middle ground.

    Can You Buy a Home in Memphis With $10,000 Down?

    Often, yes, especially on lower-priced homes. Owner financing with $10,000 down in Memphis tends to work best on homes in the $70,000 to $130,000 range, where $10,000 is close to 10%. On a $250,000 home, $10,000 is only 4%, so a seller may ask for more or charge a higher rate.

    Some sellers also accept $20,000 down on mid-priced homes. Picture a family looking at a three-bedroom house listed around $180,000. A $20,000 down payment is about 11%, which many sellers consider a solid commitment. Those families are often renting at a similar monthly cost already, which is why this route appeals to them.

    The point is not to chase the lowest possible number. It’s to find a price, down payment, and monthly payment you can keep up with for years.

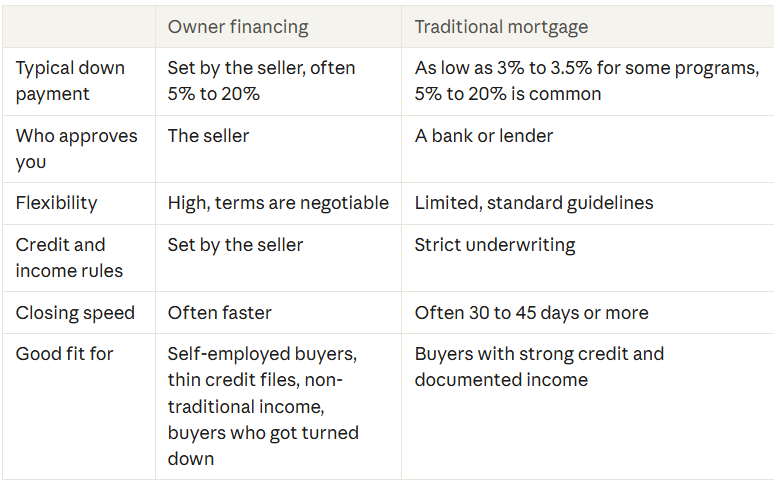
    Owner Financing vs Traditional Mortgage: How Do the Down Payments Compare?

    Bank loans can actually have lower minimums on paper. The catch is qualifying for them.

    What Else Should You Budget For Besides the Down Payment?

    The down payment isn’t the only cost. Plan for these as well:

    • Closing costs. Title work, recording fees, and attorney or closing agent fees.
    • Earnest money. A small deposit that usually goes toward your down payment.
    • Home inspection. Usually a few hundred dollars and worth every cent.
    • Homeowners insurance. Required by most sellers, and often due at closing.
    • Property taxes. Paid yearly or collected monthly depending on your agreement.
    • Repairs and moving costs. Set aside a cushion, especially for an older home.

    Is Owner Financing Legal in Tennessee?

    Yes. Seller financing is legal in Tennessee, and it’s a long-standing way to sell property. That said, federal and state rules can apply depending on how the deal is set up and how many owner-financed sales a seller makes. This is why a clear owner financing contract in Tennessee matters. The paperwork usually includes a promissory note, a deed of trust or land contract, and a payment schedule. Have a Tennessee real estate attorney or title company review everything before you sign. This article is general information, not legal or financial advice.

    How to Figure Out Your Down Payment in 5 Steps

    1. Count your cash. Add up savings you can use without touching your emergency fund.
    2. Set a monthly ceiling. Many buyers aim for a total housing payment around 30% of their take-home income or less, though your own numbers matter more than any rule.
    3. Run the math. Try a few down payments and prices in a calculator, like the examples above.
    4. Browse real listings. Look at houses for sale with owner financing in Memphis and note which ones fit your range.
    5. Ask for options. Request two or three versions of the terms with different down payments and rates, then choose the one that fits your budget.

    Common Mistakes to Avoid

    • Spending every dollar on the down payment and having nothing left for repairs.
    • Agreeing to a payment you can only afford if everything goes perfectly.
    • Skipping the inspection because the price looks good.
    • Not asking what happens if you miss a payment, including grace periods and late fees.
    • Signing without a title search or attorney review.
    • Assuming the first offer is the only offer. Terms are negotiable.

    Frequently Asked Questions

    How much down payment do I need for owner financing in Memphis?

    Most owner-financed homes in Memphis require 5% to 20% down, and 10% is a common starting point. Some listings advertise $10,000 or $20,000 down. The seller decides, so the amount can often be negotiated.

    Can I buy a house in Memphis with $10,000 down?

    Yes, in many cases, especially on homes priced around $70,000 to $130,000. On higher-priced homes, a seller may ask for more or adjust the interest rate.

    Is the down payment refundable?

    Generally not once the deal closes. Earnest money may be refundable under conditions written in your contract, such as a failed inspection. Read the agreement carefully and ask a Tennessee attorney if you’re unsure.

    Do I need a bank to buy a home with owner financing?

    No. In owner financing, the seller provides the financing, so you don’t need a bank loan. That’s what makes it a common option for no-bank home buying in Memphis.

    Does a bigger down payment lower my monthly payment?

    Yes. A larger down payment reduces the amount you finance, so your monthly payment and total interest both go down. On a $150,000 home, going from 5% to 20% down can lower the payment by about $165 a month at an 8% rate.

    Are interest rates higher with owner financing?

    Often they are somewhat higher than bank rates, because the seller takes on risk the bank wouldn’t. The rate is negotiable, and a larger down payment can sometimes help you get a better one.

    Do I need good credit for owner financing?

    It depends on the seller. Some sellers weigh credit lightly and focus on income, down payment, and payment history. Others do look closely at credit. Being upfront and organized helps either way.

    Can I use owner financing if I’m self-employed?

    Yes. Many self-employed buyers choose owner financing because banks often want two years of tax returns showing high income. A seller can look at your bank statements and overall stability instead.

  • Case Study: How Owner Financing Unlocked Homeownership at Vaughn Rd, Memphis, TN

    Buying a home through traditional bank loans can feel like climbing an uphill battle—especially when strict credit requirements, high interest rates, and lengthy underwriting processes stand in the way.

    At Owner to Dueño, we specialize in bridging the gap between property sellers and aspiring homeowners. By removing bank barriers, our platform enables direct seller financing (owner-to-owner deals) that make real estate accessible, transparent, and mutually beneficial.

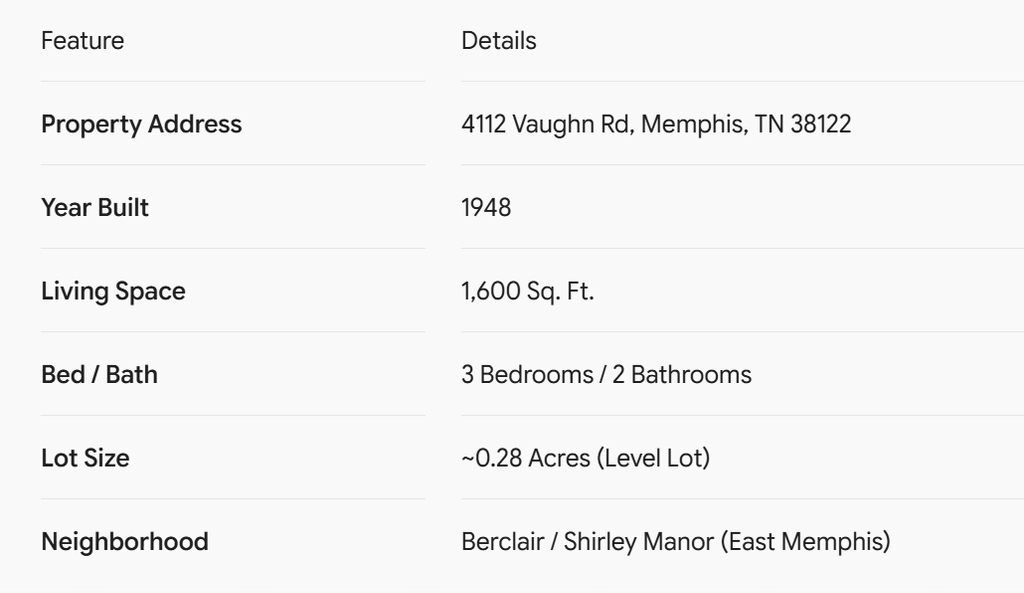
    Here is a look at how a classic 1948 mid-century residence at Vaughn Rd in Memphis, TN was successfully sold using a structured owner-financing plan.

    Property Breakdown & Local Profile

    Nestled in the 38122 ZIP code within the established Berclair / Shirley Manor area of East Memphis, this single-family home offers solid construction and an ideal location near major city arteries, parks, and local schools.

    The Challenge

    Traditional mortgage lenders often reject buyers who have strong income and steady employment but lack a lengthy conventional credit history or standard documentation. On the seller’s side, waiting for bank approvals can lead to dropped contracts, high closing fees, and months of sitting on the market.

    For 4112 Vaughn Rd, the goal was clear:

    1. Fast-track the closing process without relying on mortgage underwriters.
    2. Secure a reliable, committed buyer ready to invest in the property long-term.
    3. Ensure the buyer had manageable monthly payments while securing a solid initial equity position for the transaction.

    The Owner Financing Solution

    Through the Owner to Dueño direct sales model, the seller and buyer structured a straightforward owner-financed agreement tailored to both parties’ financial goals.

    Transaction Terms

    • Purchase Structure: Seller-Financed Direct Contract (Owner to Owner)
    • Down Payment: $20,000 upfront cash payment
    • Financed Amount: Remaining balance amortized over an agreed term with clear interest rates and fixed monthly payments.

    Why It Worked

    Immediate Equity: The $20,000 down payment demonstrated strong financial commitment from the buyer while providing the seller with immediate capital upfront.

    Speed & Efficiency: By bypassing traditional mortgage origination, both parties completed the deal with fewer closing costs and minimal red tape.

    Local Stability: The buyer secured a spacious 1,600 sq. ft. home built with classic 1948 brick-veneer craftsmanship in a stable Shelby County neighborhood.

    Key Takeaways for Buyers and Sellers in Memphis

    For Buyers

    Owner financing through Owner to Dueño provides a clear path to homeownership when traditional banks say no. By saving for a reasonable down payment ($20,000 in this case), you can move into a move-in-ready 3-bed, 2-bath home in Memphis, build home equity immediately, and stabilize your housing costs.

    For Sellers

    Financing a buyer directly creates passive monthly income, expands your buyer pool significantly, and allows you to close deals faster without worrying about appraisal delays or buyer loan dropouts.

    Looking to Buy or Sell Owner-Financed Homes in Memphis?

    Whether you are looking for owner-financed properties in 38122, Cordova, Bartlett, or anywhere across Shelby County, Owner to Dueño connects buyers and sellers directly for simple, secure, and accessible real estate deals.

    • Explore Listings: Visit ownertodueno.com to browse available owner-financed homes in Memphis, TN.
    • List Your Property: Learn how you can sell your home directly to buyers with flexible financing terms.

  • Welcome Home to 3771 Old Brownsville Rd: Space, Potential, and Direct Owner Financing in Bartlett, TN

    Finding a spacious home with flexible financing in the Bartlett area isn’t always easy, but 3771 Old Brownsville Rd delivers on all fronts. Whether you’re looking for room to grow, a solid long-term investment, or a path to homeownership that bypasses traditional bank hurdles, this property is a rare find.

    Property Details at a Glance

    • Address: 3771 Old Brownsville Rd, Bartlett, TN 38135
    • Bedrooms: 3
    • Bathrooms: 2
    • Square Footage: 2,953 sq. ft.
    • Year Built: 1963
    • Down Payment: $15,000.00
    • Financing: Owner-to-Owner Financing Available

    Generous Space with Classic Mid-Century Character

    Built in 1963, this home offers the solid structural layout and generous room sizes typical of mid-century construction. Spanning nearly 3,000 square feet, the property gives you incredible flexibility:

    • Spacious Living Areas: Plenty of square footage to create a open-concept main floor, formal dining setup, or dedicated family room.
    • 3 Comfortable Bedrooms & 2 Full Baths: Generous room sizes with substantial closet space.
    • Flexible Square Footage: Extra space can easily host a home office, recreation room, workshop, or hobby area.

    Why Bartlett, TN (38135)?

    Located in Shelby County, the 38135 area of Bartlett is known for its strong community feel, convenient amenities, and easy commute options throughout Greater Memphis.

    • Convenience: Quick access to major routes, shopping centers, dining, and local parks.
    • Established Neighborhood: Enjoy tree-lined streets and a settled community atmosphere.
    • Value: Bartlett remains one of the most sought-after suburban areas in the region.

    The Big Advantage: Owner-to-Owner Financing

    Skip the hassle of conventional mortgage applications, stringent credit checks, and long closing delays.

    With Owner-to-Owner Financing and an accessible $15,000 down payment, your route to homeownership is direct and straightforward:

    1. Simpler Process: Deal directly with the owner without third-party lender friction.
    2. Faster Closing: Move in faster without waiting weeks for bank underwriting.
    3. Accessible Ownership: A practical option if you’re self-employed, building credit, or prefer direct seller terms.
  • How Does Owner Financing Work in Memphis? A Buyer’s Complete Guide

    Owner financing means the person selling the house lends you the money to buy it. Instead of going to a bank for a mortgage, you make monthly payments directly to the seller. You still own the home — the title can be in your name from day one — but the seller holds the financial note instead of a bank.
    It’s a legitimate, legal way to buy a home in Tennessee. For buyers who don’t qualify for traditional loans, it’s often the only path to homeownership.

    What Owner Financing Is — and How It’s Different from a Bank Loan

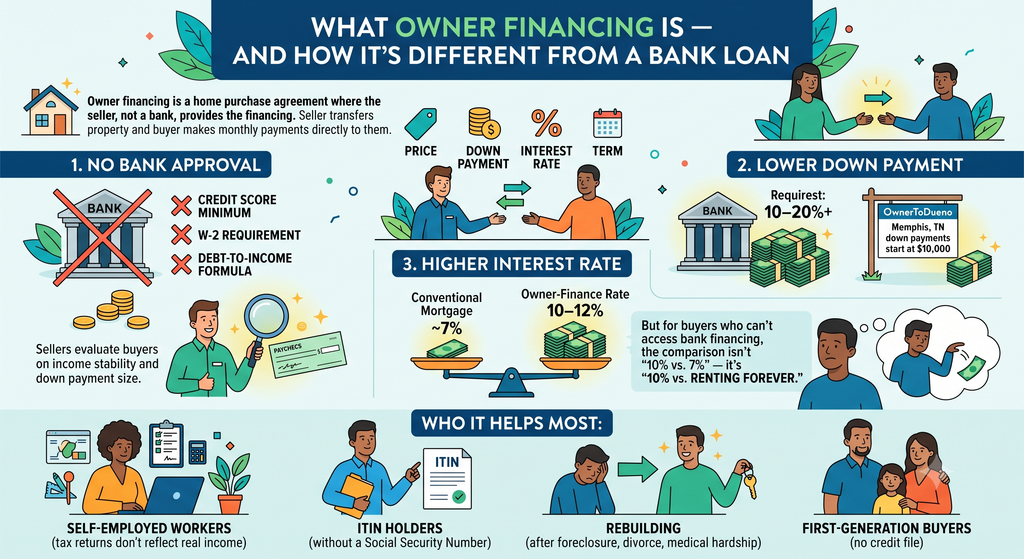
    Owner financing is a home purchase agreement where the seller, not a bank, provides the financing. The seller and buyer agree on a price, down payment, interest rate, and term. The seller transfers the property, and the buyer makes monthly payments directly to them.

    The main differences from a bank loan:

    No bank approval. No credit score minimum, no W-2 requirement, no debt-to-income formula. Sellers evaluate buyers on income stability and down payment size.

    Lower down payment. Banks require 10–20%+. On OwnerToDueno listings in Memphis, down payments start at $10,000.

    Higher interest rate. Owner-finance rates in Memphis run 10–12% — higher than a conventional mortgage. But for buyers who can’t access bank financing at any rate, the comparison isn’t “10% vs. 7%” — it’s “10% vs. renting forever.”

    Who it helps most: Self-employed workers whose tax returns don’t reflect real income. ITIN holders without a Social Security Number. Buyers rebuilding after foreclosure, divorce, or medical hardship. First-generation buyers with no credit file.

      How the Process Works: Step by Step

      Step 1 — Find a property. Browse ownertodueno.com. Every listing shows the asking price, down payment, estimated monthly payment, and property details. Current inventory runs from $159,000 in North Memphis (38128) to $289,000 in Cordova (38018).
      Step 2 — Contact the team. A team member walks you through the exact terms: down payment, interest rate, 30-year term, and estimated monthly payment.
      Step 3 — Submit your application. Not a credit check — a verification of income and available down payment. Bank statements or pay stubs work. Response in 24–48 hours.
      Step 4 — Agree on terms in writing. Purchase price, down payment, fixed interest rate (10–12%), 30-year term, monthly payment amount, and the default process. Read this section carefully.
      Step 5 — Close at a licensed title company. Every OwnerToDueno transaction closes through Bradsher, Albert & Stuart, PLLC — a licensed Tennessee attorney firm and title company in Memphis. They conduct the title search, hold your down payment in escrow, record the deed of trust with Shelby County, and give both parties every signed document.
      Step 6 — Make monthly payments and build equity. After closing, you’re the homeowner — you maintain the property, pay taxes and insurance, and make improvements. After 30 years, the note is paid off and the property is fully yours.

      Common Risks and Misunderstandings

      “The seller can take my house back whenever they want.”

      Not with a properly recorded deed of trust. The seller must go through Tennessee’s formal foreclosure process — months of legal procedure, required notices. The protection is the recording. If anyone asks you to sign without a title company, walk away.

      “Owner financing is a scam.”

      It can be — when done informally, without a recorded contract. The protection is always the same: close through a licensed title company, get a recorded contract, keep your paperwork.

      “I’ll definitely own the title from day one.”

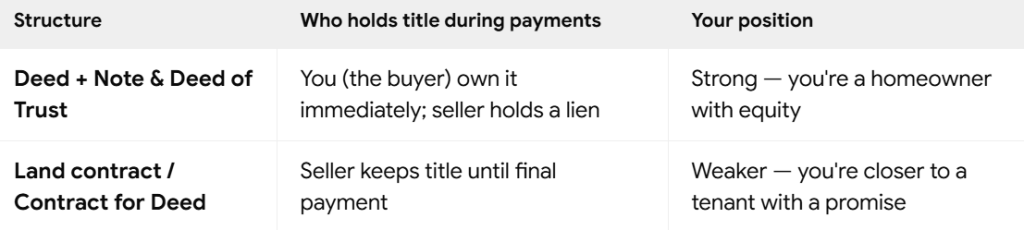
      Depends on the contract. With a warranty deed: title transfers to you at closing, seller holds a lien. With a contract for deed (land contract): seller retains title until a specified amount is paid. Both are legal in Tennessee — know which one you’re signing.


      “The rate is too high.”

      10–12% is higher than a bank rate. But if you’re currently paying $1,500/month in rent and building zero equity, a $1,600/month owner-finance payment that builds ownership is a different financial picture entirely.

      “Missing a payment won’t matter.”

      It works exactly like a bank mortgage. After a grace period you go into default. Private lenders have more flexibility than banks — but only if you communicate early.

      Frequently Asked Questions

      Do I need a Social Security Number to use owner financing in Memphis?

      No. An ITIN is sufficient to sign contracts and take title to property in Tennessee. Many OwnerToDueno buyers are ITIN holders who pay taxes, have stable income, and have been renting for years. Owner financing is the path that works for them.

      What down payment do I need?

      Down payments on OwnerToDueno listings start at $10,000. Properties in the $200,000–$289,000 range typically require $15,000–$20,000. The exact amount is on each property listing page.

      Who holds the title during the financing period?

      In most OwnerToDueno transactions, the title transfers to the buyer at closing via a warranty deed. The seller holds a lien — a deed of trust — not the title itself. Your name is on the property from day one.

      What if I want to sell before the note is paid off?

      Most owner-finance contracts include a due-on-sale clause. When you sell, the proceeds pay off the remaining balance to the seller. You keep whatever equity is above that — same as paying off a bank mortgage at sale.

      Can sellers list owner-financed properties on OwnerToDueno?

      Yes. OwnerToDueno connects sellers who want to carry financing with qualified buyers. Every transaction still closes through a licensed title company, protecting both sides.

      Ready to Buy or List?

      Browse current owner-financed homes at ownertodueno.com — Cordova, Bartlett, South Memphis, Midtown, and across the Memphis metro, down payments starting at $10,000.

    1. 5 Red Flags to Watch for in Owner-Financed Contracts (Memphis Dueño a Dueño Real Estate Guide)

      You found the house. The seller says yes. No bank, no credit check, no six weeks of underwriting.

      For thousands of Memphis families, that moment feels like the door finally opening. And it should. Dueño a dueño real estate — buying directly from an owner who finances the sale himself — has helped hardworking people in Frayser, Raleigh, Whitehaven, and Hickory Hill become homeowners when traditional lenders said no.

      But here’s the truth nobody puts on a yard sign: the contract you sign matters more than the price you negotiate.

      We’ve seen buyers in Memphis hand over $15,000 down and three years of payments, only to learn the deed was never going to be theirs. We’ve seen sellers get burned too. Almost every one of those disasters was preventable — because the warning signs were sitting right there in the paperwork.

      Below are the five red flags we tell every buyer to look for before signing an owner-financed contract in Shelby County.

      Why Owner Financing Is Growing Fast in Memphis Right Now

      Memphis has one of the most affordable housing markets among major U.S. metros, and that affordability is exactly why seller financing keeps expanding here in 2026.

      Three local forces are driving it:

      • Bank standards haven’t loosened. Self-employed buyers, cash-paid workers, and families with thin credit files still get denied — even when they can clearly afford a $900 monthly payment.
      • Older housing stock scares lenders. Much of Memphis’s inventory in neighborhoods like Berclair, Nutbush, and Orange Mound was built before 1970. Conventional and FHA appraisals routinely flag roofs, foundations, and electrical panels. Sellers finance because the bank won’t.
      • Sellers want steady income. In a market with fluctuating rates, a landlord in Parkway Village or Hickory Hill would often prefer to collect a note payment rather than manage another rental.

      That’s the good news. The risk is that Tennessee gives sellers a lot of freedom in how they structure these deals — and freedom cuts both ways.

      Red Flag #1: The Deed Isn’t Clearly Addressed

      What it looks like: The contract says you’ll “receive the deed when the balance is paid,” with no explanation of who holds title in the meantime — or the document never uses the word deed at all.

      This is the single most damaging red flag in dueño-a-dueño transactions.

      There are two very different structures out there:

      Neither is automatically illegal. But you need to know which one you’re signing, and land contracts require far more caution.

      Protect yourself: Ask directly — “Am I getting the deed at closing?” If the answer is no, insist the contract be recorded with the Shelby County Register of Deeds so your interest is on public record. An unrecorded contract is nearly invisible if the seller later sells, refinances, or dies.

      Red Flag #2: A Balloon Payment Buried in the Fine Print

      What it looks like: “Payments of $875 monthly for 60 months, remaining balance due at maturity.”

      Read that again. That last clause means after five years of on-time payments, you owe the entire remaining balance — often $80,000 or more — in one lump sum.

      Balloon payments aren’t a scam by themselves. Most owner-financed deals in Memphis use them, because few sellers want to wait 30 years. The red flag is when nobody explains it, or when the term is unrealistically short.

      What to look for:

      • A balloon due in less than 3 years is aggressive. You may not have enough payment history or repaired credit to refinance in time.
      • No written payoff schedule showing your balance each year.
      • A seller who says “don’t worry, we’ll just renew it” — but won’t put renewal terms in writing.

      Protect yourself: Negotiate for at least a 5-year balloon and a written extension option. Then start working on refinance eligibility from month one.

      Red Flag #3: Property Taxes and Insurance Are Left Vague

      Shelby County has some of the higher effective property tax rates in Tennessee, and inside Memphis city limits you’re paying both city and county taxes. On a modest $130,000 home, that’s a real number — and insurance costs have climbed sharply across the Mid-South after recent storm seasons.

      What it looks like: The contract lists a monthly payment but never says who pays taxes and insurance, or says the seller “will handle it” with no escrow account.

      Here’s the danger: if the seller is supposed to pay the taxes and quietly stops, the property can end up in a Shelby County tax sale — while you’re still making payments on time. Same story with insurance. If the house burns and there’s no valid policy, the loss can land on you.

      Protect yourself:

      • Require the contract to state exactly who pays taxes and insurance.
      • Ask for proof of payment every year (a receipt, a declarations page).
      • Verify current tax status yourself through the Shelby County Trustee before you sign.
      • Get your own policy listing you as an insured party whenever the structure allows it.

      Red Flag #4: A Harsh Forfeiture Clause

      What it looks like: “If Buyer fails to make any payment within 10 days, this agreement terminates, Buyer forfeits all payments made and all improvements, and shall vacate immediately.”

      This clause is why families lose everything over one bad month.

      Under a strict forfeiture provision on a land contract, a single late payment can theoretically wipe out your down payment, every installment you’ve made, and the new roof you paid for. Tennessee courts don’t always enforce these clauses that harshly — especially when a buyer has substantial equity — but you do not want to be fighting that battle in Chancery Court with your family’s savings on the line.

      Protect yourself: Negotiate for a cure period of at least 30 days, written notice of default sent by certified mail, and — ideally — language that requires a formal foreclosure process rather than instant forfeiture. A seller who refuses any cure period at all is telling you something about their intentions.


      Red Flag #5: The Seller Still Has a Mortgage — and Won’t Talk About It

      What it looks like: You ask, “Is there a loan on this property?” and get a vague answer, a subject change, or “that’s already handled.”

      Many Memphis owner-financed homes are sold with an existing mortgage still in place (a “wrap”). That isn’t automatically a deal-killer, but it introduces serious exposure:

      • Nearly every mortgage has a due-on-sale clause, letting the lender demand full payoff when the property transfers.
      • If the seller collects your payment and doesn’t pay their lender, the bank can foreclose — and you can lose a home you never missed a payment on.

      Protect yourself: Run a title search. Always. It costs a fraction of what you’re investing and reveals mortgages, liens, unpaid contractor claims, code enforcement judgments, and heirship problems — the last one being extremely common with inherited Memphis properties.

      If there’s an underlying loan, ask for a third-party servicing arrangement so your payment goes to a neutral company that pays the lender first. That single step eliminates most wrap-around horror stories.


      Bonus Warning Signs Worth a Second Look

      • “We don’t need a title company.” You do. Always close through a title company or real estate attorney.
      • Cash-only, no receipts. Pay by check, transfer, or servicer. Create a paper trail.
      • Pressure to sign today. Legitimate sellers give you time to review.
      • Verbal promises only. “I’ll fix the HVAC after closing” means nothing unless it’s in the contract.
      • The seller isn’t on the deed. Confirm the person signing actually owns the property.

    2. Memphis Real Estate Investing: 10–12% Yields via Owner Financing

      Memphis Real Estate Investing: 10–12% Yields via Owner Financing

      Ask any real estate investor working the Memphis market—from Frayser and Orange Mound over to Cordova and Hickory Hill—and they will tell you the same thing: buying local rental property is the easy part. The real challenge starts after the closing papers are signed.

      You probably bought your Shelby County rentals for the exact reasons everyone else does—predictable cash flow, affordable entry prices, and a massive pool of long-term renters.

      But if you’ve been managing these properties for more than a few years, you’ve likely realized that “passive income” rarely feels passive. Between tracking down late rent checks, managing rising property insurance premiums in Tennessee, dealing with the latest broken HVAC unit, and watching property management fees eat up 10% of your gross margins, landlording can quickly turn into a stressful second job.

      Fortunately, there is a better way to capture the high yields of the Memphis market without ever dealing with a single maintenance emergency or eviction court date. Sophisticated local investors are quietly shifting away from traditional renting and moving into the Dueño a Dueño (DAD) model.

      By structuring compliant owner financing, you stop playing the role of the stressed landlord and step into the most profitable position on the balance sheet: you become the bank.

      The Operational Shift: Trading Tenants for Homeowners

      When you sell a property using the DAD owner-financing framework, your entire relationship with the resident changes. You aren’t signing a standard 12-month lease with a tenant; you are signing a legal promissory note and a deed of trust with a homebuyer.

      Because they now legally own the home, the operational liabilities that used to drain your bank account completely vanish:

      Zero Maintenance or CapEx Expense: If a water heater bursts in a rental property at 2:00 AM, you pay for it. Under the DAD model, that property belongs to the buyer. All maintenance, structural repairs, and roofing upgrades are entirely their responsibility.

      No Property Management Costs: Since there are no tenants to manage or maintenance tickets to dispatch, you don’t need a middleman. You instantly save the 8% to 10% monthly cut typically charged by local property management firms.

      An End to the Turnover Cycle: The average Memphis renter moves out every 12 to 24 months. Every time they leave, you lose a month of rent and spend thousands on paint, flooring, and repairs just to make the property presentable again. DAD buyers are making a long-term commitment to a home they intend to keep for decades.

      Understanding the Numbers: The Memphis DAD Deal Breakdown

      How does a note portfolio deliver 10% to 12% fixed yields while regular rental yields continue to shrink? It comes down to premium interest rates and strong, upfront cash down payments.

      Many hardworking Memphis families—such as self-employed contracting business owners, local landscaping operators, and stable ITIN holders—are completely locked out of traditional bank mortgages due to rigid, automated algorithmic lending requirements. However, they possess excellent household incomes and substantial cash reserves. Because they are locked out of traditional banks, they gladly pay a premium interest rate for alternative financing.

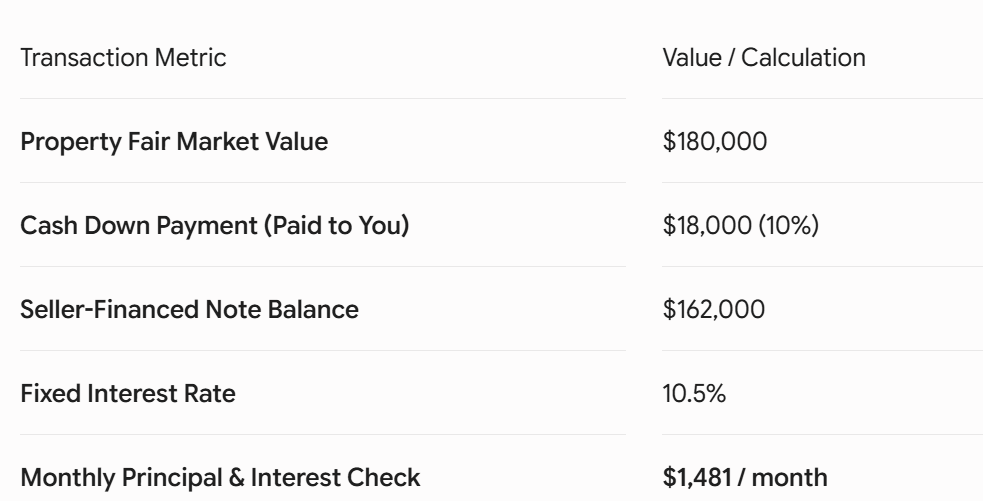
      Let’s look at how a typical property transaction stacks up in Shelby County:

      Memphis real estate

      If you kept that exact same $180,000 house as a standard rental, it might pull in $1,450 a month in gross rent. But look closely at what happens to that money before it reaches your pocket:

      • Minus property management fees ($145)
      • Minus a standard monthly maintenance/CapEx reserve ($150)
      • Minus vacancy buffers ($75)
      • Actual Net Cash Flow: Drops to around $1,080

      With the DAD note model, your $1,481 check is 100% net profit. The buyer is legally responsible for paying the annual property taxes to the Shelby County Trustee and maintaining homeowners insurance. Your monthly check arrives clean, untouched by unexpected operational bills.

      Vetting Buyers: Equity is Your Security Blanket

      A common question among local real estate circles is: “If a buyer can’t get a traditional bank loan from a commercial lender, aren’t they too high of a credit risk?”

      In a traditional mortgage environment, an automated computer program rejects anyone without a standard W-2 or a perfect FICO score. This leaves out thousands of reliable, cash-flowing families right here in Memphis.

      The DAD model relies on a much safer metric: massive upfront skin in the game.

      By requiring non-refundable down payments of $10,000 to $20,000 (or more), these families are putting down substantial equity on day one. They do not view themselves as renters who can easily walk away from a security deposit; they view themselves as homeowners who have invested their life savings into an asset. They take pride in the home, maintain it meticulously, and treat their monthly note payment as their absolute highest financial priority.

      Tax Advantages: Defer Capital Gains Taxes

      If you sell your appreciated Memphis rental properties the traditional way on the MLS, you face a major financial hurdle: the capital gains tax. Selling a property outright triggers an immediate, hefty tax bill from the IRS on all your accumulated depreciation and equity gains.

      Defer Taxes Using an Installment Sale

      By transitioning your properties into a DAD note portfolio, you can structure the exit as an Installment Sale. Instead of paying taxes on your entire gain in year one, you spread the tax liability over the lifetime of the note under IRS Form 6252. You only pay taxes on the small portion of principal you receive each year, keeping the rest of your money actively compounding at that lucrative 10% to 12% interest rate.

      Step Back from Day-to-Day Management

      You don’t have to liquidate your entire real estate portfolio and leave the Memphis market just to escape the stress of landlording. You simply need to reposition where you sit on the transaction. Moving your investments from volatile rental units into predictable, fixed-rate note portfolios lets you secure stable, double-digit cash flow without the operational headaches.

      At Owner to Dueño, we take care of the entire lifecycle of this transition. We handle local compliance, market your property to cash-ready buyers within the bilingual community, and help you structure secure, legally binding owner-financed notes right here in Shelby County.

      Ready to upgrade your cash flow?

      Let’s look at your current inventory. Connect with Owner to Dueño Today to discover how easily you can convert your active tenant headaches into entirely passive monthly interest checks.