Category: Uncategorized

  • 7 Things to Check Before You Sign an Owner Financing Contract in Memphis

    Quick answer: Before you sign an owner financing contract in Memphis, confirm seven things: the total price and interest rate, the down payment, the monthly payment and any balloon payment, who pays property taxes and insurance, how the title is handled, the condition of the home, and exactly what happens if you miss a payment. Get all of it in writing, and have a real estate attorney read the paperwork.

    Owner financing is simple on the surface. You buy the home directly from the owner, you pay them each month, and no bank is involved. That is exactly why it works for so many Memphis families. It is also why the contract matters so much. With no bank underwriter checking the file, you are the one who has to read it closely.

    Browse the homes on Dueño a Dueño right now, and you will see the structure in action. Each listing shows a total price and a monthly payment side by side, from homes under $100,000 to larger properties above $600,000. Here is how to look at any one of them with clear eyes.

    1. The total price and the interest rate

    Start with the number everyone remembers, then look one line below it. Ask for the purchase price, the interest rate, and the length of the loan, and ask to see them written down together. Two homes with the same price can cost very different amounts over time if the rate or the term is different.

    A good question to ask: “If I make every payment on schedule, what will I have paid in total by the last month?” A seller who is confident in the deal will answer that without hesitation.

    2. The down payment

    Owner financed homes often ask for a smaller down payment than a bank would. Some Memphis listings advertise low entry points, and one current listing on our site mentions a $10,000 down payment. Down payments vary by home and by seller, so always ask what is required for the specific property.

    Also ask where the down payment goes. It should be recorded in the contract as a payment toward the purchase, with a receipt.

    3. The monthly payment, and any balloon payment

    Your monthly payment should be easy to understand: how much, due on what date, paid to whom, and by what method. Then ask the question that surprises people most often: is there a balloon payment?

    A balloon payment means that after a set number of years, the remaining balance is due all at once. Some owner financing deals include one, and some do not. If yours does, know the date, know the amount, and have a plan, such as refinancing with a bank once your credit history is stronger.

    4. Who pays property taxes and insurance

    With a bank mortgage, taxes and insurance are often rolled into the monthly payment. With owner financing, the contract has to say who handles them. Make sure you know:

    • Who pays the Shelby County property tax bill, and when it is due
    • Whether homeowners insurance is required, and who is listed on the policy
    • Whether those costs are built into your payment or paid separately

    A missed tax bill can become a serious problem for both buyer and seller, so settle this before closing, not after.

    5. How the title is handled

    This is the step people skip, and it is one of the most important. Ask for a title search to confirm that the seller truly owns the home and that no other loans, liens, or unpaid taxes are attached to it. Then ask how the sale will be recorded so your ownership interest is protected on paper.

    Using a title company or a real estate attorney to close the deal is a smart way to keep the paperwork clean for everyone.

    6. The condition of the home

    Direct purchases are often “as-is,” which means repairs become your responsibility after closing. Pay for an independent inspection before you commit, even if the home looks great in the photos. Look closely at the roof, the HVAC system, plumbing, electrical, and the foundation, since those are the repairs that cost the most.

    If the inspection finds problems, you can ask the seller to fix them, lower the price, or you can walk away.

    7. What happens if you miss a payment

    Nobody likes to plan for this one, but read it anyway. A fair contract spells out the due date, any grace period, any late fee, and the steps the seller can take after a missed payment. Ask whether you can catch up on a late payment, and how long you would have to do it.

    Also ask whether on-time payments are reported to the credit bureaus. If they are, owner financing can help you build credit while you build equity.

    Quick comparison: what to ask on any owner-financed home

    What to checkQuestion to askWhere it should appear
    Price and rateWhat is my total cost over the full term?Promissory note
    Down paymentHow much, and how is it recorded?Purchase agreement
    Monthly paymentIs there a balloon payment, and when?Promissory note
    Taxes and insuranceWho pays, and who is on the policy?Contract terms
    TitleIs the title clear of liens?Title search report
    ConditionWhat did the inspection find?Inspection report
    Default termsWhat happens if I am late?Contract terms

    Frequently asked questions

    Is owner financing legal in Tennessee?

    Yes. Sellers in Tennessee can sell a home directly to a buyer and accept payments over time. Because rules can differ depending on how a deal is structured, have a Tennessee real estate attorney review your documents.

    Do I need a bank to buy a home with owner financing?

    No. In an owner-financed sale, the seller acts as the lender, so you do not need a traditional bank mortgage.

    Can I get owner financing with less-than-perfect credit?

    Often, yes. Sellers set their own requirements, so many look at the whole picture, including income and down payment, instead of only a credit score. Requirements vary by seller and property.

    What is a balloon payment?

    It is a larger lump-sum payment due at the end of a set period, covering the remaining loan balance. Not every owner financing deal has one, so ask early.

    Should I get an inspection on an owner-financed home?

    Yes. Many direct sales are as-is, so an inspection protects you from paying for hidden repairs after closing.

    What areas does Dueño a Dueño cover?

    Our listings are centered in Memphis and the surrounding area, including Bartlett, Cordova, Germantown, Collierville, Southaven, and Olive Branch.

    Ready to look at homes?

    You can browse available homes, start your application, or schedule a time to talk with our team. Prefer Spanish? Everything on the site is available in Spanish too. Hablamos español.

    If you own a home and want to sell it directly with owner financing, see our page 
  • A 3-Bedroom Brick Home in Olive Branch, MS: How Owner Financing Could Open the Door to Homeownership

    A Property Spotlight and Buyer Case Study | Olive Branch, Mississippi 38654

    For many families, finding the right home is only half the challenge. The other half is figuring out how to buy it.

    A buyer might have a steady job, enough money saved for a down payment, and a clear idea of where they want to live, yet still struggle to qualify for a traditional mortgage. Sometimes the issue is credit history. Other times, it is the bank’s lending requirements or the time it takes to get approved.

    That is why homes offered with owner financing deserve a closer look.

    At 9172 Lakeshore Dr, Olive Branch, MS 38654, the appeal starts with a classic brick exterior, three bedrooms, two bathrooms, and hardwood flooring. For someone searching for a comfortable home in the Olive Branch area, this property presents an opportunity to explore a different path toward homeownership through owner-to-owner financing.

    Let’s look at what makes this home worth considering and how a financing arrangement directly with a property owner could change the buying experience.

    The Property: A Brick Home With Everyday Appeal

    Some homes stand out because of extravagant upgrades. Others appeal to buyers because they offer the practical features people want in their everyday lives.

    This property falls into the second category.

    The three-bedroom, two-bathroom layout offers flexibility for a family, a couple who needs an extra room for working from home, or a homeowner who wants space for visiting relatives. The hardwood flooring adds warmth and character, while the brick exterior gives the home a traditional appearance.

    Here is a quick overview of the property:

    • Location: 9172 Lakeshore Dr, Olive Branch, MS 38654
    • Bedrooms: 3
    • Bathrooms: 2
    • Exterior: Brick
    • Interior feature: Hardwood flooring
    • Financing opportunity: Owner financing, subject to current availability and agreed terms

    For a buyer, the goal is not simply to find a house with enough bedrooms. It is to find a place that fits their budget, daily routine, and longer-term plans.

    Of course, buyers should confirm the home’s current condition, square footage, included appliances, and other details before making a decision.

    The Buyer Challenge: When a Mortgage Approval Becomes the Biggest Obstacle

    Imagine a prospective buyer living in the Memphis metropolitan area who wants to settle in Olive Branch.

    This buyer has a reliable income and has been saving money for a down payment. They are tired of renting and want the stability of a home they can call their own. They begin searching for three-bedroom homes, compare neighborhoods, and calculate what they can reasonably afford each month.

    Then comes the mortgage application.

    Despite being financially prepared in some respects, the buyer encounters lending requirements that make purchasing through a conventional mortgage difficult. Perhaps their credit history needs more time to improve, or their financial circumstances do not fit the lender’s approval criteria.

    This is a frustrating position to be in. The buyer may be capable of making regular payments but still cannot secure the financing needed to complete the purchase.

    This example is illustrative, not a documented customer story. It represents a challenge that some prospective homebuyers experience.

    For buyers in this situation, exploring owner financing may be a useful next step.

    The Alternative: Buying Directly From the Property Owner

    Owner financing changes who provides the financing.

    Instead of relying entirely on a traditional mortgage lender, a buyer may enter into a financing agreement directly with the property owner. The buyer and seller agree on the purchase price, down payment, interest rate, repayment schedule, and other contract terms.

    The exact structure depends on the transaction. Not every seller offers owner financing, and not every applicant will qualify.

    For a property such as 9172 Lakeshore Dr, the first step would be to confirm that the home is currently available and that the seller is offering owner financing. The buyer would then need to review the proposed terms and determine whether the arrangement fits their financial situation.

    For someone who has struggled to obtain a conventional mortgage, this approach may offer another route worth investigating.

    It is important to understand that owner financing does not automatically mean no credit review, no income requirements, or guaranteed approval. Those details depend on the seller’s criteria and the written agreement.

    Why This Three-Bedroom Home Could Be Worth Exploring

    A home purchase is about more than financing. The property itself needs to make sense for the person buying it.

    1. Three bedrooms provide flexibility

    Three bedrooms can accommodate a variety of living arrangements. A family may use all three as sleeping spaces, while another buyer might turn one into a home office or hobby room.

    That flexibility can make a home more useful as household needs change.

    2. Two bathrooms can make daily life easier

    Having two bathrooms can be particularly helpful for households with multiple occupants. It can make busy mornings less stressful and provide additional convenience when family or friends visit.

    3. Hardwood flooring brings warmth and character

    Hardwood flooring is a feature many buyers appreciate for its natural appearance. Depending on its condition and maintenance history, it may also offer long-term durability.

    Before purchasing, buyers should inspect the flooring and ask whether any repairs or refinishing are needed.

    4. A brick exterior offers a classic look

    Brick homes remain popular with buyers who appreciate traditional residential architecture. However, the exterior should still be inspected for cracks, moisture issues, and signs of needed maintenance.

    The key is to evaluate the home’s actual condition rather than make assumptions based on its appearance.

    Looking at the Purchase Like a Real Buyer

    Let’s return to our illustrative buyer.

    Instead of focusing only on whether a bank will approve a mortgage, the buyer begins by asking a different set of questions:

    • Is the home available for purchase?
    • Is owner financing actually offered for this property?
    • How much money is required upfront?
    • What are the interest rate, monthly payment, and repayment period?
    • Are property taxes, homeowners insurance, maintenance, and any applicable association fees included in the payment or paid separately?
    • What happens if a payment is late or the buyer wants to pay off the balance early?
    • What legal rights does the buyer receive under the proposed agreement?

    These questions help turn a general interest in a property into a practical buying decision.

    The buyer should also review the complete agreement with a qualified real estate attorney before signing. Understanding the contract is essential, particularly when the financing arrangement differs from a conventional mortgage.

    The goal is not simply to get into a house. It is to enter an agreement the buyer can realistically afford and understand.

    The Numbers Matter More Than the Sales Pitch

    One of the biggest mistakes a homebuyer can make is concentrating on the down payment while overlooking the total cost of ownership.

    A lower upfront payment may sound appealing, but the buyer still needs to understand the interest rate, payment schedule, and full amount that will be paid over time.

    For example, two financing offers may require similar down payments but produce very different monthly payments because of differences in interest rates, repayment periods, and other costs.

    Before moving forward with 9172 Lakeshore Dr, a prospective buyer should request a written breakdown of the proposed financing terms.

    That breakdown should clearly explain the purchase price, down payment, principal financed, interest rate, monthly payment, repayment term, taxes, insurance, and any additional charges.

    There is no need to guess at these numbers. A good buying decision starts with transparent terms and a realistic household budget.

    What This Case Study Teaches Us About Owner Financing

    Even without assuming that a particular buyer has already purchased this home, the scenario illustrates an important point: the traditional mortgage process is not the only financing arrangement a buyer may want to investigate.

    Owner financing can create an alternative when a seller is willing to finance a purchase and the buyer meets the agreed requirements.

    But it is not a shortcut around the need for careful financial planning. Buyers still need to compare costs, inspect the property, understand their contractual rights, and determine whether they can comfortably manage the payments.

    For the right buyer and the right transaction, a direct arrangement between a property owner and a homebuyer may create an opportunity that would otherwise be difficult to pursue.

    That is the value of looking beyond the usual mortgage route.

    Is 9172 Lakeshore Dr the Right Home for You?

    If you are searching for a three-bedroom, two-bathroom brick home in Olive Branch, Mississippi, 9172 Lakeshore Dr is an address worth investigating based on the features described here.

    The hardwood flooring, practical bedroom count, and traditional exterior provide a starting point for evaluating the property. The possibility of owner financing may also interest buyers who want to explore alternatives to conventional bank financing.

    Before making plans, confirm the property’s current listing status and financing availability. Public property records do not necessarily reflect an active listing, so neither should be assumed without verification.

    If the home is available with owner financing, take time to review the terms, inspect the property, and make sure the agreement supports your long-term financial goals.

    At OwnerToDueno.com, the broader idea behind owner-to-owner homebuying is simple: help buyers explore another possible path to homeownership by connecting the property purchase with financing options offered directly by owners.

    Your next home may be closer than you think. Start by asking the right questions, understanding your options, and finding a purchase arrangement that makes sense for you.

    Property details and financing availability should be independently confirmed before publication or before a buyer relies on this information. This article is an educational property spotlight and illustrative case study, not a report of a verified buyer transaction or a guarantee of financing approval.

  • Available | Owner-Financed House: Amanda Oaks Circle N, Memphis, TN 38141

    Finding good homes for sale nearby with flexible terms may seem difficult sometimes. If you have problems with traditional mortgage conditions, a low credit score, or endless bank documents, then Owner to Dueño has some great news for you.

    The house located at Amanda Oaks Circle N, Memphis, TN 38141 is available to buy right now with direct owner financing from Owner to Dueño and low down payments.

    Why This Amanda Oaks Circle N House Is Unique

    Constructed in 1993, the single-family house boasts 1,090 square feet of comfortable living space. Located in a nice, peaceful neighborhood, this house is a great choice for being close to all amenities in Southeast Memphis and Shelby County.

    Property Highlights:

    Roomy layout: 3 bedrooms, 2 full bathrooms, and 1,090 sq ft of interior space.

    Built in 1993: Reliable house with low-maintenance interior and exterior features.

    Comfortable Living: A cozy family room that is ready to provide comfortable rest and leisure.

    Functional Kitchen: An effective kitchen area with enough cabinets and workspace.

    Private Driveway Parking: A separate off-street driveway parking area.

    Large Yard Area: A great backyard area perfect for outdoor fun with the family.

    Location: Memphis 38141

    The ZIP code 38141 is a convenient and easily accessible residential area of the Memphis metro region.

    • By living at Amanda Oaks Circle N, you will be able to reach the following destinations in just minutes:
    • Various retail centers, groceries, and local restaurants.
    • Public and private schools and parks.

    How Owner-to-Owner Financing Works with Owner to Dueño

    Traditionally, buying a property involves lengthy pre-approvals from banks, perfect credit histories, and waiting for a long time. At Owner to Dueño, we eliminate these obstacles by providing direct owner financing services.

    • Advantages of Buying Properties Through Owner to Dueño:
    • No Bank Pre-Approvals Needed: Skip strict lender requirements and avoid bank rejections.
    • Flexible Entry Conditions: Move into your new home with flexible down payment opportunities.
    • Simple Paperwork: Only direct paperwork between you and the seller of the property.
    • Direct Ownership: Build equity in your new house right away.

    Frequently Asked Questions (FAQ)

    What is the current status of the Amanda Oaks Circle N property?
    Currently, this property is AVAILABLE for direct owner financing from Owner to Dueño.

    Is there any necessity of good credit or bank pre-approval to buy the property?
    No, since Owner to Dueño provides direct owner financing without bank qualifying or good credit score.

    How to Buy This Property?
    You can contact the Owner to Dueño team directly in order to discuss down payment conditions, make an appointment for a viewing, and sign the owner financing contract.

    Take the Next Step Toward Ownership
    Properties with direct owner-to-owner financing in the 38141 ZIP code are sold really fast. Contact Owner to Dueño right now and get more information about the Amanda Oaks Circle N property!

  • Evitando el Banco: Cómo las Familias de Memphis Están Comprando Casas “Dueño a Dueño”

    Evitando el Banco: Cómo las Familias de Memphis Están Comprando Casas “Dueño a Dueño”

    Encontrar una buena casa en el área de Memphis no es la parte difícil. Ya sea que estés buscando en un vecindario tranquilo y establecido en Bartlett, una espaciosa casa familiar de 4 habitaciones en Cordova, o una propiedad clásica más cerca del corazón de Memphis, las opciones están ahí afuera.

    El verdadero desafío es lidiar con los bancos.

    Para los dueños de negocios locales, contratistas independientes o cualquier persona que esté trabajando duro para reconstruir su historial de crédito, los prestamistas hipotecarios tradicionales pueden hacer que el sueño de tener casa propia parezca completamente inalcanzable. El papeleo interminable, las exigencias de los analistas de crédito y los sistemas automatizados suelen decir “no” antes de evaluar tu verdadera capacidad financiera.

    Pero no necesitas un préstamo bancario tradicional para comprar una casa en el condado de Shelby. Los compradores y vendedores locales están descubriendo una alternativa más rápida y justa: el financiamiento por el propietario, o transacciones directas dueño a dueño.

    ¿Qué es el Financiamiento por el Propietario? Es simple. En lugar de pedir un préstamo enorme a un banco para pagarle al vendedor, le compras la casa directamente al dueño de la propiedad. Acuerdan un pago inicial (down payment) y los términos mensuales entre ustedes, y le pagas directamente al dueño. El banco queda fuera del proceso por completo.

    Por Qué los Compradores Locales Están Evitando los Bancos en Memphis, Cordova y Bartlett

    1. Flexibilidad Real con el Crédito

    Memphis es una ciudad construida sobre el trabajo duro y el emprendimiento. Si manejas tu propio negocio, trabajas en logística o tienes una empresa de servicios locales, es muy probable que tus declaraciones de impuestos no encajen en los moldes estrictos de un banco. Con el financiamiento de dueño a dueño, los vendedores se fijan en tu capacidad real de pago actual, tu estabilidad laboral y tu compromiso con la casa, no en un simple número de tres dígitos de tu puntaje de crédito.

    2. Cierre Rápido y sin Trámites Burocráticos

    Una hipoteca bancaria tradicional tarda entre 45 y 60 days en cerrarse, manteniendo tu vida en pausa mientras los analistas corporativos revisan papeles. Una transacción directa financiada por el propietario puede cerrarse en una fracción de ese tiempo porque estás tratando con un ser humano, no con una institución financiera.

    3. Deja de Pagar Renta y Empieza a Construir tu Patrimonio

    Los alquileres en Cordova y Bartlett siguen subiendo, pero ese cheque mensual solo genera riqueza para tu arrendador. Cuando compras una casa a través de financiamiento del vendedor, tus pagos mensuales se destinan a un activo que es tuyo. Obtienes la estabilidad de tener tu propia casa y la libertad de cambiarla y mejorarla como tú quieras.

    Haciendo que la Compra de Vivienda Sea Accesible para Todos

    Las barreras del idioma y la cultura no deberían impedir que seas dueño de una propiedad en tu comunidad. Una de las mayores ventajas de trabajar con Owner to Dueño es nuestro compromiso con un mercado inmobiliario claro, transparente y completamente bilingüe.

    Comprar una casa es una de las decisiones financieras más importantes de tu vida. Mereces entender cada paso del proceso, cada línea del contrato y cada detalle de tu plan de pagos, ya sea que prefieras hacer negocios en inglés o en español.

    Encuentra tu Casa de Venta Directa en el Condado de Shelby

    El camino para dejar de rentar y convertirte en propietario no tiene por qué pasar por la oficina de un banco corporativo. Si estás buscando una forma directa y de humano a humano para comprar tu próxima propiedad, el financiamiento por el propietario abre las puertas que los prestamistas tradicionales cierran.

    En Owner to Dueño, nos especializamos en conectar directamente a compradores y vendedores locales, trayendo opciones transparentes de financiamiento por el dueño al mercado de Memphis.

    ¿Listo para dejar de rentar? Revisa nuestras últimas propiedades de venta directa en Memphis, Cordova y Bartlett, y toma el control de tu futuro financiero hoy mismo.


    Are you ready to transition from renter to homeowner? At Owner to Dueño, we understand that the buying process can feel overwhelming, which is why we guide you every step of the way in your preferred language. Buy your home owner-to-owner, with zero bank interference and total transparency. Explore our available properties today!

  • Bypassing the Bank: How Memphis Families Are Buying Homes “Dueño a Dueño”

    Bypassing the Bank: How Memphis Families Are Buying Homes “Dueño a Dueño”

    Finding a great home in the Memphis area isn’t the hard part. Whether you are looking at a quiet, established neighborhood in Bartlett, a spacious 4-bedroom family home in Cordova, or a classic property closer to the heart of Memphis, the houses are out there.

    The real challenge? Dealing with the banks.

    For local business owners, self-employed contractors, or anyone working hard to rebuild their credit score, traditional mortgage lenders can make homeownership feel completely out of reach. The endless paperwork, rigid underwriters, and strict automated systems often say “no” before they even look at your actual financial capability.

    But you don’t need a traditional bank loan to buy a house in Shelby County. Local buyers and sellers are discovering a faster, fairer alternative: owner financing, or direct dueño a dueño transactions.

    What is Owner Financing? It’s simple. Instead of getting a massive loan from a bank to pay the seller, you buy the home directly from the property owner. You agree on a down payment and monthly terms together, and you pay the owner directly. The bank is cut out of the loop entirely.

    Why Local Buyers are Skipping the Bank in Memphis, Cordova, and Bartlett

    1. True Credit Flexibility

    Memphis is a city built on hard work and entrepreneurship. If you run your own business, work in logistics, or operate a local service, your tax returns might not fit into a bank’s neat little boxes. With owner-to-owner financing, sellers look at your actual ability to pay today, your job stability, and your commitment to the home—not just a single three-digit credit score.

    2. Fast Closing Without the Red Tape

    A traditional bank mortgage takes anywhere from 45 to 60 days to close, keeping your life in limbo while corporate underwriters shuffle papers. A direct owner-financed transaction can close in a fraction of that time because you are dealing with a human being, not an institution.

    3. Stop Paying Landlords, Start Building Equity

    Rent across Cordova and Bartlett keeps climbing, but that monthly check only builds wealth for your landlord. When you buy a home through seller financing, your monthly payments go toward an asset you own. You get the stability of homeownership and the freedom to truly make the house your own.

    Making Homeownership Accessible to Everyone

    Language and cultural barriers shouldn’t keep you from owning a piece of your community. One of the biggest advantages of working with Owner to Dueño is our commitment to clear, transparent, and completely bilingual real estate.

    Buying a home is one of the biggest financial decisions you will ever make. You deserve to understand every step of the process, every line of the contract, and every detail of your payment schedule—whether you prefer to do business in English or Spanish.

    Find Your Direct-Sale Home in Shelby County

    The path from renting to owning doesn’t have to go through a corporate bank tower. If you are looking for a straightforward, human-to-human way to purchase your next property, owner financing opens doors that traditional lenders close.

    At Owner to Dueño, we specialize in connecting local buyers and sellers directly, bringing transparent owner-financed options straight to the Memphis market.

    Ready to stop renting? Check out our latest direct-sale listings across Memphis, Cordova, and Bartlett, and take control of your financial future today.


    ¿Listo para dar el paso de inquilino a propietario? En Owner to Dueño entendemos que el proceso de compra puede ser complicado, por eso te ayudamos en tu propio idioma. Compra tu casa de dueño a dueño, sin intermediarios bancarios y con total transparencia. ¡Explora nuestras propiedades disponibles hoy mismo!

  • Rompiendo las barreras del banco: Por qué el financiamiento de dueño a dueño es el futuro de la vivienda en Memphis

    Rompiendo las barreras del banco: Por qué el financiamiento de dueño a dueño es el futuro de la vivienda en Memphis

    Hablemos con total honestidad por un momento. El proceso tradicional de compra de una vivienda está roto para muchísimas personas trabajadoras.

    Encuentras la casa de tus sueños, calculas tu presupuesto y sabes perfectamente que puedes cubrir los pagos mensuales. Pero en cuanto entras a un banco tradicional, te cierran la puerta en la cara. Tal vez un historial de crédito inestable de hace unos años te está frenando. Tal vez trabajas por cuenta propia (self-employed) y tus declaraciones de impuestos no encajan en los moldes tan rígidos del banco. O tal vez, esa montaña interminable de trámites burocráticos parece imposible de superar.

    En Dueño A Dueño, no creemos que el rechazo de un banco deba significar el fin de tu sueño de tener casa propia.

    Existe una manera más rápida, sencilla y mucho más humana de comprar una casa: el Financiamiento de Dueño a Dueño (también conocido como financiamiento por el vendedor). Si ya estás cansado de pagar una renta que solo hace crecer la riqueza de alguien más, aquí te explicamos por qué eliminar al intermediario podría ser la mejor decisión financiera de tu vida.


    ¿Qué es exactamente el financiamiento de dueño a dueño?

    En una transacción inmobiliaria común, el banco actúa como el intermediario. Ellos le pagan al vendedor y tú te pasas los siguientes 15 o 30 años devolviéndole el dinero al banco con intereses altísimos.

    Con el financiamiento de dueño a dueño, eliminas por completo al banco de la ecuación.

    En lugar de pedir una hipoteca a una institución financiera, le compras la casa directamente al propietario actual. Ambos se ponen de acuerdo en el precio de compra, el pago inicial (down payment) y la estructura de las mensualidades. Tú le haces los pagos mensuales directamente al vendedor (o a través de un servicio de procesamiento) hasta que la casa sea completamente tuya.

    Es un contrato directo y transparente entre dos personas. Sin costos corporativos exagerados, sin tarifas ocultas del banco y sin tener que esperar meses a que un evaluador apruebe tu vida.


    Los grandes beneficios: Por qué los compradores en Memphis están cambiando de estrategia

    Para muchas familias de nuestra comunidad, el financiamiento directo no es solo una alternativa; es una experiencia mucho mejor. Estas son las razones:

    • Flexibilidad con el crédito: Los vendedores son personas reales, no algoritmos. A ellos les importa mucho más tu ingreso actual, tu estabilidad laboral y tu compromiso de pago, que un simple número de tres dígitos en tu puntaje de crédito.
    • Evita la trampa del trabajo independiente: Si tienes tu propio negocio, trabajas por contrato o en la economía informal, los bancos te hacen dar mil vueltas para demostrar tus ingresos. Los vendedores evalúan tu capacidad real de pago, lo que permite que el proceso avance sin trabas.
    • Costos de cierre drásticamente menores: Las hipotecas tradicionales vienen cargadas de comisiones bancarias por apertura, procesamiento y gastos administrativos que suman miles de dólares. Al no usar un banco, ese dinero se queda en tu bolsillo.
    • Rapidez: Al no tener que esperar por tasaciones bancarias, comités de crédito ni verificaciones infinitas de documentos, un trato financiado por el dueño a menudo se puede cerrar en una fracción del tiempo.

    Construyendo patrimonio en nuestras comunidades

    Cuando recorremos Memphis, vemos vecindarios llenos de vida y de familias que quieren echar raíces profundas. Sin embargo, cuando los sistemas de préstamo tradicionales excluyen a la gente, toda la comunidad sale perdiendo.

    El financiamiento de dueño a dueño equilibra la balanza. Logra que el mercado inmobiliario local sea más flexible, humano y accesible. Les da a las familias la oportunidad de dejar de rentar, empezar a acumular plusvalía (el valor real de tu propiedad menos lo que debes) y, finalmente, ser dueñas de un pedazo de su propia comunidad.

    ¿Estás listo para encontrar tu hogar?

    No necesitas una solicitud bancaria perfecta para convertirte en propietario. Solo necesitas un vendedor dispuesto, un contrato claro y un camino directo hacia adelante.

    En Dueño A Dueño, diseñamos nuestra plataforma digital segura para ser el puente que une a compradores y vendedores. Ya sea que busques una venta en efectivo, una renta directa o una propiedad financiada por el dueño, estamos aquí para ayudarte a tomar el control de tu futuro de vivienda.

    Explora nuestros listados más recientes de propiedades directas aquí en Memphis y encuentra el camino hacia tu propia casa que realmente funcione para ti.

  • Breaking the Bank Barrier: Why Owner-to-Owner Financing is the Future of Homeownership in Memphis

    Breaking the Bank Barrier: Why Owner-to-Owner Financing is the Future of Homeownership in Memphis

    Let’s be completely honest for a second. The traditional home-buying process is broken for a lot of hard-working people.

    You find a house you love, you calculate your budget, and you know you can afford the monthly payments. But then you walk into a traditional bank, and the door slams shut. Maybe a fluctuating credit score from a few years ago is holding you back. Maybe you are self-employed, and your tax returns don’t fit into the bank’s rigid little boxes. Or maybe the endless mountain of red tape just feels impossible to climb.

    At Dueño A Dueño, we don’t believe a bank rejection should mean the end of your homeownership dream.

    There is a faster, simpler, and much more human way to buy a home: Owner-to-Owner Financing (also known as seller financing). If you are tired of paying rent that builds someone else’s wealth, here is why bypassing the middleman might be the best financial move you ever make.


    What Exactly is Owner-to-Owner Financing?

    In a standard real estate transaction, a bank acts as the middleman. They give the seller the money, and you spend the next 15 to 30 years paying the bank back with heavy interest.

    With Owner-to-Owner financing, you completely cut the bank out of the equation.

    Instead of getting a mortgage from a financial institution, you buy the home directly from the current owner. You both agree on a purchase price, a down payment, and a monthly payment structure. You make your monthly payments directly to the seller (or a processing service) until the house is completely yours.

    It’s a direct, transparent contract between two individuals. No corporate overhead, no hidden bank fees, and no waiting months for an underwriter to approve your life.


    The Big Benefits: Why Memphis Buyers are Making the Switch

    For many families in our community, direct financing isn’t just an alternative—it’s a much better experience. Here is why:

    • Credit Flexibility: Sellers are real people, not algorithms. They care much more about your current income, your job stability, and your commitment to making payments than a single three-digit credit score.
    • Bypassing the Self-Employed Trap: If you run your own business, contract, or work in the gig economy, banks make you jump through endless hoops to prove your income. Sellers look at your actual ability to pay, keeping the process moving forward.
    • Drastically Lower Closing Costs: Traditional mortgages come loaded with bank origination fees, processing fees, and administrative costs that add up to thousands of dollars. Eliminating the bank keeps that cash in your pocket.
    • Speed: Without a bank waiting on third-party appraisals, credit committees, and endless paperwork verification, an owner-financed deal can often close in a fraction of the time.

    Building Wealth in Our Communities

    When we look around Memphis, we see vibrant neighborhoods filled with people who want to put down deep roots. But when traditional lending systems lock people out, it hurts the whole community.

    Owner-to-owner financing levels the playing field. It keeps local real estate flexible, human, and accessible. It gives families the chance to stop renting, start building equity, and finally own a piece of their community.

    Ready to Find Your Home?

    You don’t need a perfect bank application to become a homeowner. You just need a willing seller, a clear contract, and a direct path forward.

    At Dueño A Dueño, we built our secure digital marketplace to be the bridge that brings buyers and sellers together. Whether you are looking for a cash sale, a direct rental, or an owner-financed property, we are here to help you take control of your housing future.

    Explore our latest dire

  • ¿Trabajas por Cuenta Propia? Cómo el Financiamiento por Dueño Directo Te Ayuda a Evitar el Obstáculo de los 2 Años de Impuestos

    Ser tu propio jefe es el verdadero sueño americano. Tú decides tus horarios, eliges a tus clientes y construyes algo completamente tuyo. Sin embargo, cuando llega el momento de comprar una casa, los bancos tradicionales suelen tratar a los emprendedores independientes como un riesgo en lugar de una historia de éxito.

    Si alguna vez has intentado solicitar una hipoteca convencional siendo trabajador independiente, contratista o dueño de negocio, es muy probable que te hayas topado con una pared difícil de superar: el requisito obligatorio de presentar los dos últimos años de declaraciones de impuestos.

    Por suerte, los préstamos bancarios tradicionales no son el único camino hacia la compra de una vivienda. Una transacción de dueño a dueño —conocida comúnmente como financiamiento por dueño o financiamiento del vendedor— ofrece una alternativa flexible y práctica que evalúa tu realidad financiera real, no solo tus deducciones de impuestos.


    El Problema: Por Qué las Hipotecas Tradicionales Castigan a los Emprendedores

    Los prestamistas tradicionales dependen de un proceso de evaluación sumamente rígido. Para aprobar un préstamo estándar, el banco solo le pide a un empleado con nómina (W-2) unos cuantos talones de pago recientes. En cambio, a los trabajadores independientes les exigen un mínimo de dos años consecutivos de declaraciones de impuestos federales.

    Aquí es donde los dueños de negocios caen en una trampa financiera:

    • La Paradoja de las Deducciones: Un buen contador maximizará las deducciones legales de tu negocio para reducir el pago de tus impuestos. Aunque esto te ahorra dinero ante el gobierno, disminuye tus “ingresos netos” sobre el papel.
    • La Perspectiva del Banco: Si tu negocio generó $150,000 en ingresos brutos, pero después de las deducciones tu ingreso neto reportado es de $40,000, el banco calculará tu capacidad de pago basándose únicamente en esos $40,000.
    • Transiciones Recientes: Si dejaste un trabajo corporativo hace doce meses para lanzar un negocio muy exitoso, un banco te rechazará de inmediato por el simple hecho de no tener el historial de dos años requeridos, sin importar cuánto dinero tengas guardado en tu cuenta corriente.

    La Solución: Cómo el Financiamiento por Dueño Elimina las Trabas Burocráticas

    En una transacción de bienes raíces financiada por el dueño, el vendedor de la propiedad actúa como el prestamista. En lugar de que una enorme corporación bancaria dicte las reglas, los términos del acuerdo se negocian directamente entre tú (el comprador) y el propietario del inmueble.

    Como el vendedor no está atado a las estrictas regulaciones bancarias federales, tiene la libertad de evaluar tu salud financiera desde una perspectiva lógica y del mundo real.

    1. Pruebas Alternativas de Ingresos

    Mientras que un banco solo se fija en la última línea de tus impuestos, un vendedor particular suele estar más que dispuesto a verificar tu capacidad de pago mediante otros métodos. Puedes demostrar un flujo de caja saludable presentando:

    • Entre 12 y 24 meses de estados de cuenta bancarios (personales o del negocio) que muestren depósitos constantes.
    • Un estado de Pérdidas y Ganancias (P&L) certificado y preparado por tu contador.
    • Un historial sólido de pagos puntuales de alquiler residencial o comercial.

    2. Haz Valer Tu Dinero en Efectivo, No Tus Papeles

    Los vendedores que ofrecen financiamiento directo buscan, ante todo, seguridad. Si tienes un buen pago inicial (down payment) ahorrado, ese dinero habla más fuerte que un historial fiscal de dos años. Un enganche fuerte le demuestra al vendedor que estás totalmente comprometido y que adquieres capital inmediato en la propiedad, lo que les da la tranquilidad necesaria para estructurar un plan de pagos mensuales cómodo y flexible para ti.

    3. Acelera Tu Proceso de Compra

    En lugar de esperar dos años fiscales completos —e intencionalmente pagar de más en tus impuestos solo para mostrarle ingresos netos más altos a un banco—, el financiamiento por dueño te permite comprar una casa hoy mismo. Esto representa una enorme ventaja en mercados inmobiliarios competitivos como Memphis, Cordova o Bartlett, donde los precios de las viviendas siguen subiendo mientras tú esperas en el banquillo.


    Cómo Estructurar un Acuerdo de Dueño a Dueño de Forma Segura

    Aunque los tratos directos de dueño a dueño ofrecen una flexibilidad increíble, proteger tu inversión requiere un enfoque transparente y profesional. Una transacción estándar y segura incluye los siguientes pasos clave:

    • Acordar los Términos: Tú y el vendedor negocian el precio de compra, el pago inicial, la tasa de interés y la duración del préstamo.
    • El Plan de Pago Globo (Balloon Payment): La mayoría de los contratos financiados por el dueño incluyen un “pago globo” que vence después de 3 a 7 años. Esto te otorga tiempo suficiente para acumular plusvalía, consolidar el historial fiscal de tu negocio y refinanciar fácilmente con una hipoteca tradicional más adelante.
    • Utilizar una Empresa de Custodia Profesional (Escrow): Contrata siempre a una compañía de títulos autorizada o a un abogado de bienes raíces para que se encargue del cierre, la investigación del título de propiedad y el registro de la escritura. Tus pagos mensuales deben gestionarse a través de una empresa de servicios de préstamos (terceros) para garantizar que tu historial de pagos quede registrado legalmente.

    No Permitas que las Trabas de una Hipoteca Frenen el Crecimiento de Tu Negocio

    Tu capacidad para hacer crecer un negocio debería ser una ventaja al comprar una casa, no un castigo. Al evitar los obstáculos institucionales tradicionales, los tratos de dueño a dueño permiten a los emprendedores asegurar la estabilidad de tener casa propia bajo términos que realmente se adaptan al estilo de vida de un empresario moderno.

    ¿Estás listo para encontrar una propiedad sin tener que pasar por los laberintos de los bancos? Explora hoy mismo listados verificados de dueño a dueño en tu área a través de Owner to Dueño y conéctate directamente con vendedores que valoran el potencial real de tu negocio.

  • Self-Employed? How Owner Financing Can Bypass the 2-Year Tax Return Hurdl

    Being your own boss is the ultimate American dream. You set your hours, choose your clients, and build something entirely your own. But when it comes time to buy a home, traditional banks often treat self-employed entrepreneurs like a liability rather than a success story.

    If you’ve ever tried to apply for a conventional mortgage as a freelancer, business owner, or independent contractor, you’ve likely hit a brick wall known as the two-year tax return hurdle.

    Fortunately, traditional bank loans aren’t the only path to homeownership. An owner-to-owner transaction—commonly known as owner financing or seller financing—offers a flexible, practical alternative that evaluates your financial reality, not just your tax write-offs.


    The Problem: Why Traditional Mortgages Punish Entrepreneurs

    Traditional lenders rely on a rigid underwriting process. To qualify for a standard loan, a bank requires a W-2 employee to show a few recent paystubs. But for the self-employed, they demand a minimum of two consecutive years of federal tax returns.

    Here is where the trap closes on business owners:

    • The Write-Off Paradox: A good accountant will maximize your legal business deductions to reduce your taxable income. While this saves you money at tax time, it lowers your “net income” on paper.
    • The Bank’s View: Even if your business generated $150,000 in gross revenue, if your net income after deductions shows as $40,000, the bank calculates your borrowing power based solely on that lower $40,000 figure.
    • Recent Transitions: If you recently left a corporate job to launch a highly successful business twelve months ago, a bank will automatically reject you because you lack the magic two-year track record—regardless of how much cash you have in the bank.

    The Solution: How Owner Financing Sweeps the Red Tape Aside

    In an owner-financed real estate transaction, the property seller acts as the lender. Instead of a massive bank corporation dictating the terms, the agreement is negotiated directly between you (the buyer) and the property owner.

    Because the seller isn’t bound by strict federal banking regulations, they can look at your financial health through a practical, real-world lens.

    1. Alternative Proof of Income

    While a bank only looks at the bottom line of your tax return, a private seller is often perfectly happy to verify your ability to pay through alternative means. You can easily prove a healthy cash flow by providing:

    • 12 to 24 months of corporate or personal bank statements showing consistent deposits.
    • A certified Profit & Loss (P&L) statement prepared by your accountant.
    • A steady history of on-time commercial or residential rent payments.

    2. Leverage Your Cash, Not Your Paperwork

    Sellers offering owner financing are primarily looking for security. If you have a solid down payment saved up, that cash talks louder than a perfect two-year tax history. A strong down payment shows the seller that you have “skin in the game” and immediate equity in the property, making them much more comfortable structuring a flexible monthly payment plan for you.

    3. Fast-Track Your Timeline

    Instead of waiting two full fiscal years—and intentionally overpaying on your taxes just to show a higher net income to a bank—owner financing allows you to buy a home right now. This is a massive advantage in competitive real estate markets like Memphis, Cordova, or Bartlett, where home prices continue to rise while you wait on the sidelines.


    How to Structure an Owner-Financed Deal Safely

    While owner-to-owner deals offer incredible flexibility, protecting yourself requires a transparent, professional approach. A standard, safe transaction involves a few key steps:

    • Agree on the Terms: You and the seller negotiate the purchase price, the down payment, the interest rate, and the length of the loan.
    • The Balloon Payment Plan: Most owner-financed deals include a “balloon payment” due after 3 to 7 years. This gives you plenty of time to build equity, establish your business’s official tax history, and easily refinance into a traditional mortgage later down the road.
    • Use Professional Escrow: Always hire a licensed title company or real estate attorney to handle the closing, title search, and deed recording. Your monthly payments should go through a third-party loan servicing company to ensure your payment history is legally documented.

    Don’t Let a Mortgage Matrix Hold Your Business Back

    Your ability to grow a business should be an asset when buying a home, not a penalty. By bypassing traditional institutional hurdles, owner-to-owner deals empower entrepreneurs to secure the stability of homeownership on terms that make sense for a modern business owner.

    Ready to find a property without dealing with traditional bank loops? Explore verified owner-to-owner listings in your area today on Owner to Dueño and connect directly with sellers who value your business’s true potential.

  • Dueño a Dueño en Memphis, TN — Casas Disponibles en 38134 Sin Banco, Sin Crédito Mínimo

    Dueño a Dueño en Memphis, TN — Casas Disponibles en 38134 Sin Banco, Sin Crédito Mínimo

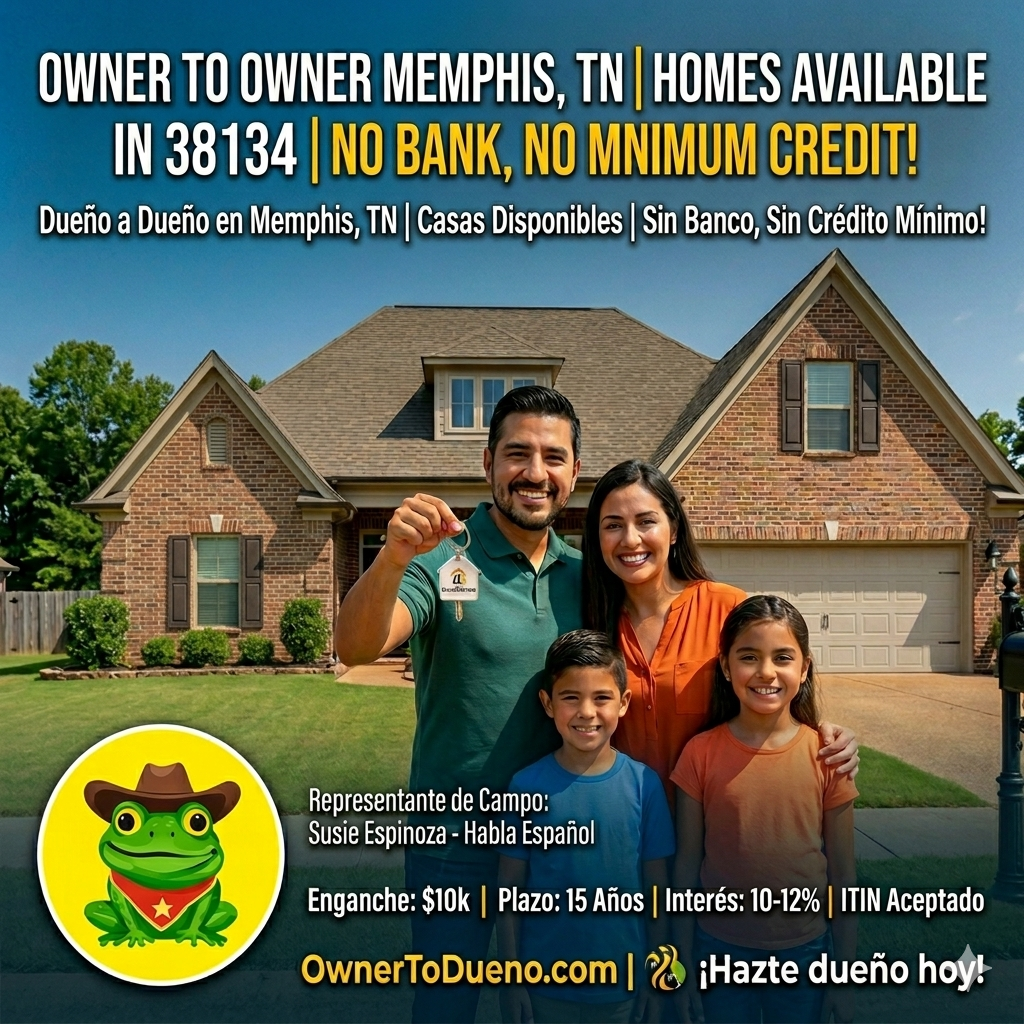
    OwnerToDueno ofrece casas con financiamiento por el dueño en Memphis, TN — incluyendo el código postal 38134 (área de Bartlett) — con un enganche de $10,000 a $20,000, un interés del 10 al 12%, plazos de 15 años, sin necesidad de banco, sin puntaje de crédito mínimo y aceptando ITIN. Propiedades como 2819 Hidden Creek Cv y 5280 Yellowood Rd en Memphis 38134 are ejemplos del tipo de viviendas disponibles a través del programa Dueño a Dueño (DAD). Contacta a OwnerToDueno.com para ver la disponibilidad actual.

    Si has estado buscando “dueño a dueño” o “dueño a dueño casas” en Memphis — has llegado a la página correcta. OwnerToDueno conecta directamente a los compradores hispanohablantes con vendedores de viviendas que están dispuestos a financiar la venta ellos mismos, sin la intervención de un banco.

    Sin puntaje FICO. Sin aprobación de hipoteca. Sin necesidad de hablar inglés. Solo un enganche, un acuerdo firmado y las llaves de una casa que te pertenece.

    ¿Qué significa “Dueño a Dueño”? / What Does “Dueño a Dueño” Mean?

    Dueño a Dueño significa owner to owner en inglés. En el sector inmobiliario, se refiere a una transacción en la que el vendedor financia la compra directamente — en lugar de que el comprador pase por un banco, la FHA o una compañía hipotecaria.

    El vendedor actúa como el prestamista. El comprador realiza los pagos mensuales directamente al vendedor (o a una empresa de servicios de depósito en garantía/escrow). Al final del plazo, el comprador es el dueño absoluto de la casa.

    Este modelo se ha utilizado en los Estados Unidos por generaciones — mucho antes de que las compañías hipotecarias se convirtieran en la vía principal para adquirir una vivienda. Es legal, ejecutable y totalmente documentado. En OwnerToDueno, cada cierre se realiza a través de una compañía de títulos autorizada en Tennessee.

    Casas en Memphis 38134 — Área de Bartlett y Stage Park

    El código postal 38134 cubre una zona residencial grande y establecida en el lado norte de Memphis — que incluye partes de Bartlett, Stage Park Meadows y Raleigh. Es una zona de Shelby County práctica y familiar: cerca de escuelas, supermercados y de importantes empleadores como el FedEx World Hub (a solo unas millas al sur por Airways Blvd).

    Las casas en el 38134 suelen tener entre 1,200 y más de 2,000 pies cuadrados — casas unifamiliares de 3 y 4 recámaras en calles tranquilas con patio. Los precios de renta en la zona rondan entre $1,600 y $1,800 al mes. Para un comprador que realiza pagos mensuales por una casa financiada por el dueño, el pago suele ser comparable al de una renta — pero cada dólar está acumulando valor e inversión propia (equity).

    Ejemplos de propiedades en el área 38134:

    • 2819 Hidden Creek Cv, Memphis TN 38134 — 3 recámaras / 2 baños, aprox. 1,228–1,300 pies cuadrados, calle sin salida (cul-de-sac) muy tranquila en el corredor de Bartlett. Renta comparable: ~$1,690/mes. Bajo un escenario de financiamiento por el dueño con $15,000 de enganche: el pago mensual sería de aproximadamente $1,050–$1,200/mes — cómprala en lugar de rentarla.
    • 5280 Yellowood Rd, Memphis TN 38134 — 4 recámaras / 2 baños, aprox. 1,814 pies cuadrados, vecindario de Stage Park Meadows. Una de las casas más grandes disponibles en este código postal. Renta comparable: ~$1,795/mes. Más espacio, el mismo camino de financiamiento por el dueño.

    Nota: La disponibilidad específica cambia constantemente. Contacta a OwnerToDueno.com para confirmar qué propiedades están disponibles actualmente para financiamiento por el dueño en el 38134.

    Cómo funciona el programa Dueño a Dueño (DAD)

    El Programa DAD de OwnerToDueno está diseñado para compradores que están listos para ser dueños — pero que no pueden usar un banco. Así es como funciona el programa:

    • Enganche: $10,000–$20,000 (dependiendo del precio de la propiedad)
    • Tasa de interés: 10–12% (fija)
    • Plazo: 15 años (amortizado)
    • Sin bancos, sin compañías hipotecarias, sin FHA
    • Sin puntaje de crédito mínimo
    • Se acepta ITIN en lugar de Número de Seguro Social (SSN)
    • Cierre a través de una compañía de títulos autorizada en Tennessee — totalmente documentado y protegido legalmente
    • Toda la comunicación en español — desde la primera visita hasta el cierre

    Por qué el financiamiento por el dueño tiene más sentido que rentar en Memphis

    Un inquilino en Memphis 38134 que paga $1,700 al mes por una casa de 3 recámaras gastará $20,400 al año — y no tendrá nada al final. En 5 años, eso representa $102,000 en pagos de renta con cero beneficios para ti.

    Un comprador en el mismo vecindario, bajo un acuerdo de Dueño a Dueño, paga una cantidad mensual similar — pero cada pago reduce el saldo de la deuda. En el año 5, ya tiene una inversión acumulada. En el año 15, es dueño de la casa por completo, libre de deudas.

    El pago mensual de una casa financiada por el dueño de $100,000 con $15,000 de enganche al 11% a 15 años es de aproximadamente $965 al mes. Eso es menos que la mayoría de las rentas en el 38134 — y estás construyendo tu propio patrimonio.

    Susie Espinoza — Representante de campo en Memphis

    Cuando un comprador califica para el programa DAD, se le agenda una cita para recorrer la propiedad en persona con Susie Espinoza, la representante de campo de OwnerToDueno en Memphis. Susie habla español de forma nativa y acompaña a los compradores personalmente en cada propiedad — sin barreras de idioma, sin confusiones y sin presiones.

    Desde la primera visita hasta la mesa de cierre, todo el proceso se lleva a cabo en español para los compradores que así lo prefieran.

    Quiénes califican

    Calificas para el programa Dueño a Dueño si:

    1. Tienes entre $10,000 y $20,000 disponibles para el enganche.
    2. Tienes ingresos estables (empleo, trabajo por cuenta propia/negocio propio o ingresos por renta).
    3. No tienes — o no puedes usar — un número de Seguro Social para fines de una hipoteca.
    4. Estás listo para tener tu propia casa en Memphis, Shelby County o las áreas circundantes.

    El puntaje de crédito no es un factor determinante. Un historial de ejecución hipotecaria (foreclosure), bancarrota o la falta de historial crediticio no te descalifica. El programa está basado en tu capacidad para realizar los pagos mensuales — no en tu reporte de crédito.

    Ver casas disponibles

    OwnerToDueno muestra las propiedades actuales con financiamiento por el dueño disponibles en Memphis y Shelby County — actualizadas regularmente. Para ver las casas en el 38134 y los códigos postales cercanos, visita la página de listados o llama/envía un mensaje de texto para que te conectemos directamente con Susie.

    OwnerToDueno.com — En español. Sin banco. Sin crédito mínimo.