Tag: memphis real estate

  • How Does Owner Financing Work in Memphis? A Buyer’s Complete Guide

    Owner financing means the person selling the house lends you the money to buy it. Instead of going to a bank for a mortgage, you make monthly payments directly to the seller. You still own the home — the title can be in your name from day one — but the seller holds the financial note instead of a bank.
    It’s a legitimate, legal way to buy a home in Tennessee. For buyers who don’t qualify for traditional loans, it’s often the only path to homeownership.

    What Owner Financing Is — and How It’s Different from a Bank Loan

    Owner financing is a home purchase agreement where the seller, not a bank, provides the financing. The seller and buyer agree on a price, down payment, interest rate, and term. The seller transfers the property, and the buyer makes monthly payments directly to them.
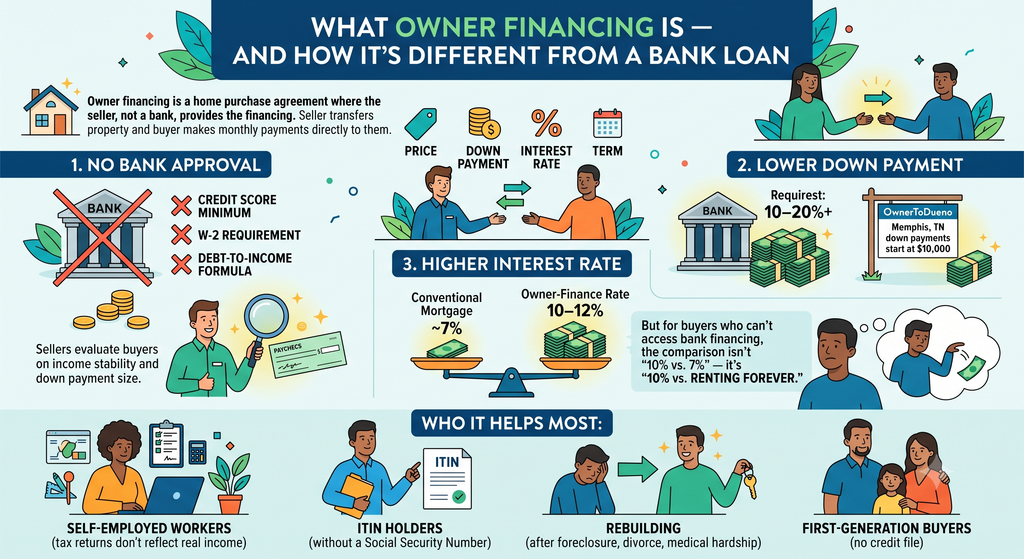
    The main differences from a bank loan:

    No bank approval. No credit score minimum, no W-2 requirement, no debt-to-income formula. Sellers evaluate buyers on income stability and down payment size.

    Lower down payment. Banks require 10–20%+. On OwnerToDueno listings in Memphis, down payments start at $10,000.

    Higher interest rate. Owner-finance rates in Memphis run 10–12% — higher than a conventional mortgage. But for buyers who can’t access bank financing at any rate, the comparison isn’t “10% vs. 7%” — it’s “10% vs. renting forever.”

    Who it helps most: Self-employed workers whose tax returns don’t reflect real income. ITIN holders without a Social Security Number. Buyers rebuilding after foreclosure, divorce, or medical hardship. First-generation buyers with no credit file.

      How the Process Works: Step by Step

      Step 1 — Find a property. Browse ownertodueno.com. Every listing shows the asking price, down payment, estimated monthly payment, and property details. Current inventory runs from $159,000 in North Memphis (38128) to $289,000 in Cordova (38018).
      Step 2 — Contact the team. A team member walks you through the exact terms: down payment, interest rate, 30-year term, and estimated monthly payment.
      Step 3 — Submit your application. Not a credit check — a verification of income and available down payment. Bank statements or pay stubs work. Response in 24–48 hours.
      Step 4 — Agree on terms in writing. Purchase price, down payment, fixed interest rate (10–12%), 30-year term, monthly payment amount, and the default process. Read this section carefully.
      Step 5 — Close at a licensed title company. Every OwnerToDueno transaction closes through Bradsher, Albert & Stuart, PLLC — a licensed Tennessee attorney firm and title company in Memphis. They conduct the title search, hold your down payment in escrow, record the deed of trust with Shelby County, and give both parties every signed document.
      Step 6 — Make monthly payments and build equity. After closing, you’re the homeowner — you maintain the property, pay taxes and insurance, and make improvements. After 30 years, the note is paid off and the property is fully yours.

      Common Risks and Misunderstandings

      “The seller can take my house back whenever they want.”

      Not with a properly recorded deed of trust. The seller must go through Tennessee’s formal foreclosure process — months of legal procedure, required notices. The protection is the recording. If anyone asks you to sign without a title company, walk away.

      “Owner financing is a scam.”

      It can be — when done informally, without a recorded contract. The protection is always the same: close through a licensed title company, get a recorded contract, keep your paperwork.

      “I’ll definitely own the title from day one.”

      Depends on the contract. With a warranty deed: title transfers to you at closing, seller holds a lien. With a contract for deed (land contract): seller retains title until a specified amount is paid. Both are legal in Tennessee — know which one you’re signing.


      “The rate is too high.”

      10–12% is higher than a bank rate. But if you’re currently paying $1,500/month in rent and building zero equity, a $1,600/month owner-finance payment that builds ownership is a different financial picture entirely.

      “Missing a payment won’t matter.”

      It works exactly like a bank mortgage. After a grace period you go into default. Private lenders have more flexibility than banks — but only if you communicate early.

      Frequently Asked Questions

      Do I need a Social Security Number to use owner financing in Memphis?

      No. An ITIN is sufficient to sign contracts and take title to property in Tennessee. Many OwnerToDueno buyers are ITIN holders who pay taxes, have stable income, and have been renting for years. Owner financing is the path that works for them.

      What down payment do I need?

      Down payments on OwnerToDueno listings start at $10,000. Properties in the $200,000–$289,000 range typically require $15,000–$20,000. The exact amount is on each property listing page.

      Who holds the title during the financing period?

      In most OwnerToDueno transactions, the title transfers to the buyer at closing via a warranty deed. The seller holds a lien — a deed of trust — not the title itself. Your name is on the property from day one.

      What if I want to sell before the note is paid off?

      Most owner-finance contracts include a due-on-sale clause. When you sell, the proceeds pay off the remaining balance to the seller. You keep whatever equity is above that — same as paying off a bank mortgage at sale.

      Can sellers list owner-financed properties on OwnerToDueno?

      Yes. OwnerToDueno connects sellers who want to carry financing with qualified buyers. Every transaction still closes through a licensed title company, protecting both sides.

      Ready to Buy or List?

      Browse current owner-financed homes at ownertodueno.com — Cordova, Bartlett, South Memphis, Midtown, and across the Memphis metro, down payments starting at $10,000.
    1. Memphis Real Estate Investing: 10–12% Yields via Owner Financing

      Memphis Real Estate Investing: 10–12% Yields via Owner Financing

      Ask any real estate investor working the Memphis market—from Frayser and Orange Mound over to Cordova and Hickory Hill—and they will tell you the same thing: buying local rental property is the easy part. The real challenge starts after the closing papers are signed.

      You probably bought your Shelby County rentals for the exact reasons everyone else does—predictable cash flow, affordable entry prices, and a massive pool of long-term renters.

      But if you’ve been managing these properties for more than a few years, you’ve likely realized that “passive income” rarely feels passive. Between tracking down late rent checks, managing rising property insurance premiums in Tennessee, dealing with the latest broken HVAC unit, and watching property management fees eat up 10% of your gross margins, landlording can quickly turn into a stressful second job.

      Fortunately, there is a better way to capture the high yields of the Memphis market without ever dealing with a single maintenance emergency or eviction court date. Sophisticated local investors are quietly shifting away from traditional renting and moving into the Dueño a Dueño (DAD) model.

      By structuring compliant owner financing, you stop playing the role of the stressed landlord and step into the most profitable position on the balance sheet: you become the bank.

      The Operational Shift: Trading Tenants for Homeowners

      When you sell a property using the DAD owner-financing framework, your entire relationship with the resident changes. You aren’t signing a standard 12-month lease with a tenant; you are signing a legal promissory note and a deed of trust with a homebuyer.

      Because they now legally own the home, the operational liabilities that used to drain your bank account completely vanish:

      Zero Maintenance or CapEx Expense: If a water heater bursts in a rental property at 2:00 AM, you pay for it. Under the DAD model, that property belongs to the buyer. All maintenance, structural repairs, and roofing upgrades are entirely their responsibility.

      No Property Management Costs: Since there are no tenants to manage or maintenance tickets to dispatch, you don’t need a middleman. You instantly save the 8% to 10% monthly cut typically charged by local property management firms.

      An End to the Turnover Cycle: The average Memphis renter moves out every 12 to 24 months. Every time they leave, you lose a month of rent and spend thousands on paint, flooring, and repairs just to make the property presentable again. DAD buyers are making a long-term commitment to a home they intend to keep for decades.

      Understanding the Numbers: The Memphis DAD Deal Breakdown

      How does a note portfolio deliver 10% to 12% fixed yields while regular rental yields continue to shrink? It comes down to premium interest rates and strong, upfront cash down payments.

      Many hardworking Memphis families—such as self-employed contracting business owners, local landscaping operators, and stable ITIN holders—are completely locked out of traditional bank mortgages due to rigid, automated algorithmic lending requirements. However, they possess excellent household incomes and substantial cash reserves. Because they are locked out of traditional banks, they gladly pay a premium interest rate for alternative financing.

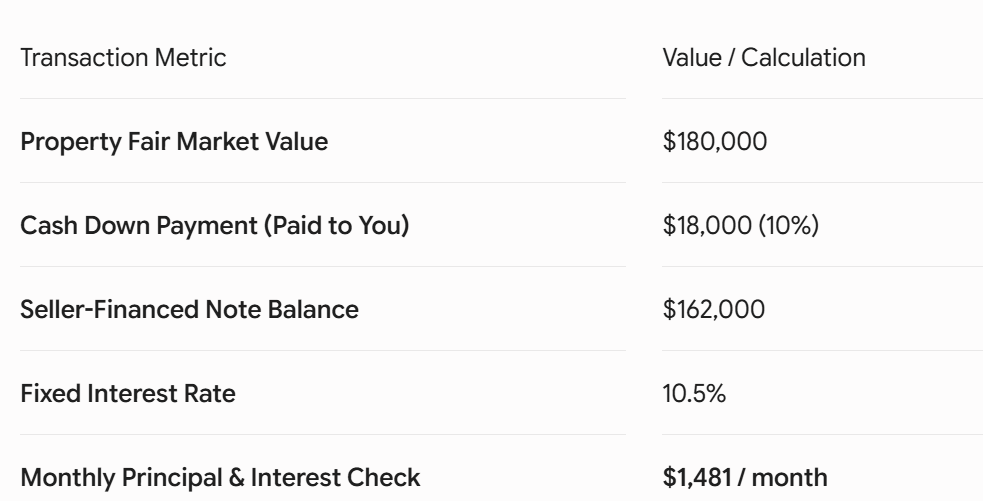
      Let’s look at how a typical property transaction stacks up in Shelby County:

      Memphis real estate

      If you kept that exact same $180,000 house as a standard rental, it might pull in $1,450 a month in gross rent. But look closely at what happens to that money before it reaches your pocket:

      • Minus property management fees ($145)
      • Minus a standard monthly maintenance/CapEx reserve ($150)
      • Minus vacancy buffers ($75)
      • Actual Net Cash Flow: Drops to around $1,080

      With the DAD note model, your $1,481 check is 100% net profit. The buyer is legally responsible for paying the annual property taxes to the Shelby County Trustee and maintaining homeowners insurance. Your monthly check arrives clean, untouched by unexpected operational bills.

      Vetting Buyers: Equity is Your Security Blanket

      A common question among local real estate circles is: “If a buyer can’t get a traditional bank loan from a commercial lender, aren’t they too high of a credit risk?”

      In a traditional mortgage environment, an automated computer program rejects anyone without a standard W-2 or a perfect FICO score. This leaves out thousands of reliable, cash-flowing families right here in Memphis.

      The DAD model relies on a much safer metric: massive upfront skin in the game.

      By requiring non-refundable down payments of $10,000 to $20,000 (or more), these families are putting down substantial equity on day one. They do not view themselves as renters who can easily walk away from a security deposit; they view themselves as homeowners who have invested their life savings into an asset. They take pride in the home, maintain it meticulously, and treat their monthly note payment as their absolute highest financial priority.

      Tax Advantages: Defer Capital Gains Taxes

      If you sell your appreciated Memphis rental properties the traditional way on the MLS, you face a major financial hurdle: the capital gains tax. Selling a property outright triggers an immediate, hefty tax bill from the IRS on all your accumulated depreciation and equity gains.

      Defer Taxes Using an Installment Sale

      By transitioning your properties into a DAD note portfolio, you can structure the exit as an Installment Sale. Instead of paying taxes on your entire gain in year one, you spread the tax liability over the lifetime of the note under IRS Form 6252. You only pay taxes on the small portion of principal you receive each year, keeping the rest of your money actively compounding at that lucrative 10% to 12% interest rate.

      Step Back from Day-to-Day Management

      You don’t have to liquidate your entire real estate portfolio and leave the Memphis market just to escape the stress of landlording. You simply need to reposition where you sit on the transaction. Moving your investments from volatile rental units into predictable, fixed-rate note portfolios lets you secure stable, double-digit cash flow without the operational headaches.

      At Owner to Dueño, we take care of the entire lifecycle of this transition. We handle local compliance, market your property to cash-ready buyers within the bilingual community, and help you structure secure, legally binding owner-financed notes right here in Shelby County.

      Ready to upgrade your cash flow?

      Let’s look at your current inventory. Connect with Owner to Dueño Today to discover how easily you can convert your active tenant headaches into entirely passive monthly interest checks.